Choosing an investment is not simply about finding the product with the highest historical return. The right NRI investment in India depends on how much capital is available, where the money originates, how soon it may be needed and whether the investor wants the proceeds to remain in India or move overseas.
Living abroad does not mean losing access to India's investment market. Non-Resident Indians (NRIs) can explore bank deposits, mutual funds, listed shares, bonds, pension products, real estate, Portfolio Management Services (PMS) and Alternative Investment Funds (AIFs), subject to applicable regulations and eligibility conditions.
A person investing ₹15 lakh may have very different priorities from an investor allocating ₹3 crore. The first may value liquidity and straightforward products, while the second may consider professionally managed or alternative strategies. Neither approach is automatically better.
This guide compares NRI investment options in India across practical wealth tiers and explains how NRIs can evaluate products, risks, costs and regulatory requirements before committing capital.
NRI Investment in India: Key Details at a Glance
| Parameter | What NRIs Should Know |
| Common investment options | Bank deposits, mutual funds, stocks, bonds, NPS, PMS, AIFs and eligible real estate |
| Main NRI bank accounts | NRE, NRO and FCNR(B) |
| PMS minimum investment | Generally ₹50 lakh for a new client |
| AIF minimum investment | Generally ₹1 crore, subject to regulatory exceptions |
| Mutual fund eligibility | NRIs can invest, subject to the scheme's terms and country-specific restrictions |
| Direct equity investment | Permitted under applicable FEMA and SEBI conditions |
| Real estate | Residential and commercial property permitted; agricultural land, plantation property and farmhouses are restricted |
| Repatriation | Depends on the investment route, source of funds, account type and applicable rules |
| Important compliance | PAN, KYC, FATCA/CRS declarations, tax documentation and bank-account requirements |
| Key decision factors | Wealth tier, investment horizon, liquidity, risk tolerance, taxation and overseas exposure |
What Should NRIs Consider Before Choosing Investment Options in India?
Before comparing products, an NRI should understand the financial and regulatory framework through which the investment will be made. These considerations influence both the available choices and the eventual movement of money.
1. NRE, NRO and FCNR(B) accounts
The three main account types serve different purposes.
| Account | Primary Purpose | Repatriation | Interest Taxability in India |
| NRE | Holding foreign earnings in Indian rupees | Principal and interest generally fully repatriable | Generally exempt in India while the account holder qualifies as a person resident outside India under FEMA |
| NRO | Managing income earned in India, such as rent, dividends and pension | Current income and eligible balances subject to applicable conditions; general balance remittance limit of USD 1 million per financial year | Taxable |
| FCNR(B) | Holding eligible foreign-currency term deposits | Generally fully repatriable | Generally exempt in India while eligible |
The NRE account is useful when an investor wants to bring overseas earnings into India while retaining repatriation flexibility. The NRO account is generally used for Indian income and domestic financial transactions. FCNR(B) deposits allow eligible foreign-currency balances to remain denominated in currencies offered by the bank.
The choice matters because NRI investment in India may be funded through different permitted routes, and the source of money can affect repatriation.
For a detailed explanation, read ALTPORT's guide to NRI repatriation rules for NRE, NRO and GIFT City investments.
2. Taxation and country of residence
Indian tax treatment is only one part of the picture. The investor's country of residence may also tax investment income or capital gains. Double Taxation Avoidance Agreements (DTAAs) may provide relief, subject to eligibility and documentation.
NRIs should consider:
- Tax deducted at source (TDS) in India.
- Capital gains treatment based on the investment and holding period.
- Interest taxation on NRO deposits.
- Tax reporting requirements in the country of residence.
- Currency conversion and foreign-exchange gains or losses.
3. Regulatory and onboarding requirements
A typical investment onboarding process may require a PAN, passport, overseas address proof, visa or residency documentation, bank details and completed KYC declarations. FATCA and Common Reporting Standard (CRS) declarations may also apply.
The exact requirements differ between banks, mutual fund houses, PMS providers and AIF managers. NRIs based in countries such as the United States and Canada may encounter additional onboarding restrictions with certain financial institutions.
Read more about DTAA provisions for NRIs investing in India.
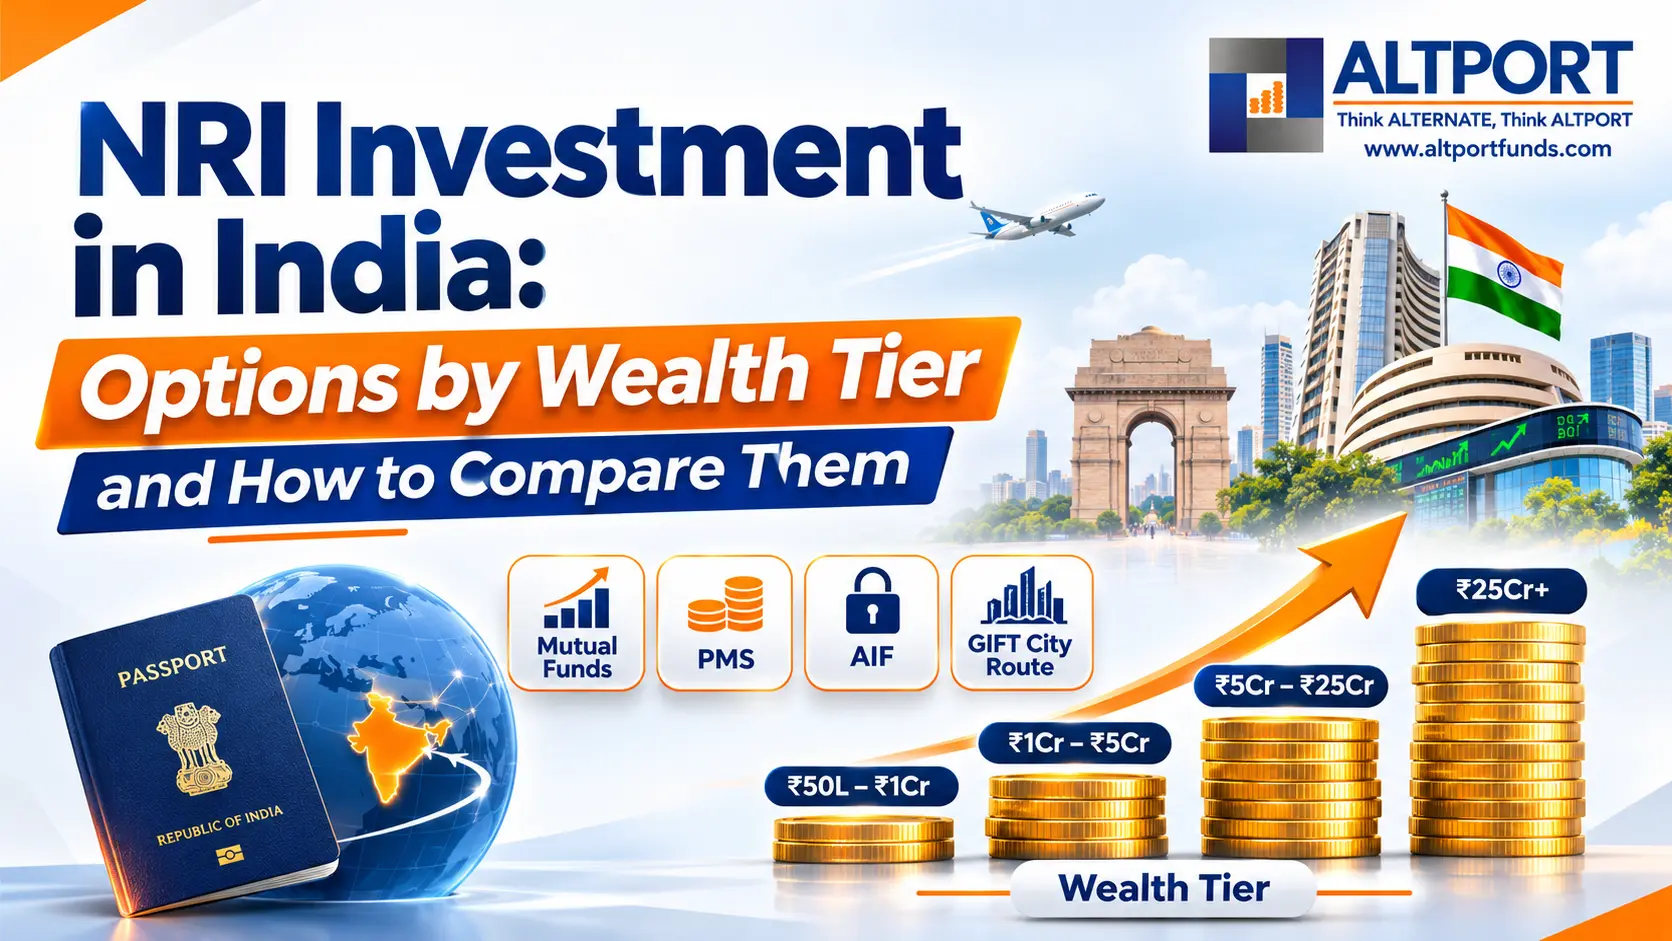
How Do NRI Investment Considerations Change by Wealth Tier?
The amount available for investment influences the range of products an NRI can practically evaluate. The following bands are planning categories, not official investor classifications or guaranteed eligibility thresholds.
Tier 1: Investable wealth below ₹50 lakh
For an investor with less than ₹50 lakh available for Indian investments, simplicity, diversification and liquidity generally deserve priority.
Potential options include:
- NRE and NRO fixed deposits: Useful for investors who want defined deposit tenures and predictable interest, subject to the applicable bank terms.
- FCNR(B) deposits: Worth evaluating when retaining foreign-currency exposure is important.
- Mutual funds: Equity, debt, hybrid and index funds can provide access to different market segments.
- Government securities: Can be considered for fixed-income exposure, subject to eligibility and the relevant investment route.
- National Pension System (NPS): An option for eligible NRIs and OCIs planning for retirement.
For this wealth tier, NRI investment in India does not need to involve complex products. A diversified mutual fund portfolio and suitable deposits may be sufficient for many investors.
PMS and most AIFs are generally outside this tier because of their minimum investment requirements.
Tier 2: Investable wealth between ₹50 lakh and ₹1 crore
This tier opens the possibility of evaluating PMS alongside mutual funds, deposits and direct equity.
PMS involves a portfolio manager managing an individual client's portfolio under an agreed mandate. Unlike a mutual fund, the investor generally holds the underlying securities in their own account.
The minimum investment for a new PMS client is generally ₹50 lakh under SEBI regulations. However, meeting the minimum does not automatically make PMS suitable. The investor should assess:
- The manager's investment philosophy.
- Portfolio concentration and sector exposure.
- Benchmark and performance measurement.
- Management and other applicable charges.
- Exit terms and portfolio liquidity.
- NRI onboarding and permitted funding arrangements.
An NRI with ₹75 lakh available, for example, could compare a diversified mutual fund allocation with a PMS mandate. The decision should depend on the investor's need for customisation, willingness to accept concentration and ability to monitor the portfolio.
Tier 3: Investable wealth between ₹1 crore and ₹5 crore
At this level, investors can evaluate a broader set of products, including AIFs, subject to eligibility and the specific fund's terms.
Most AIFs have a minimum investment requirement of ₹1 crore per investor. Certain regulatory exceptions apply, including provisions for accredited investors and specified categories of participants.
AIFs provide access to strategies that may not be available through conventional mutual funds. Depending on the category and scheme, these can include:
- Venture capital and startup investments.
- Private equity.
- Private credit and structured credit.
- Listed equity and long-short strategies.
- Special situations and other alternative strategies.
The investor should examine the fund's category, investment mandate, tenure, redemption conditions, valuation policy, fees and risk disclosures.
At this wealth level, NRI investment in India may involve a combination of traditional products, PMS and selected AIFs. However, allocating a large proportion of capital to illiquid alternatives can create cash-flow challenges. Investors should retain adequate liquidity outside such investments.
Explore Alternative Investment Funds in India and AIF investment options for NRIs to understand the relevant fund structures.
Tier 4: Investable wealth above ₹5 crore
NRIs with larger portfolios may benefit from a more structured allocation process. Instead of evaluating each product independently, they can assess the overall portfolio across Indian and overseas assets.
Possible areas of consideration include:
- Multiple PMS strategies with different investment styles.
- Selected Category I, II and III AIFs.
- Mutual funds and listed securities.
- Fixed-income instruments and deposits.
- Eligible real estate exposure.
- GIFT City funds and international investment structures, where eligible.
- Family-office or wealth-advisory support.
This is where manager diversification, asset allocation and reporting become especially important. A portfolio holding several funds with similar strategies may appear diversified by product count but remain concentrated in the same market risks.
There is no regulatory rule that makes ₹5 crore a separate investment category. It is simply a practical planning band for investors who may need a more coordinated approach to wealth management.
For larger portfolios, family office services may be relevant when investment oversight, reporting, succession planning and multi-generational wealth considerations require a coordinated structure.
What Is the Difference Between Mutual Funds, PMS and AIFs for NRIs?
These three routes offer different ownership structures, investment mandates and levels of flexibility.
| Parameter | Mutual Funds | PMS | AIFs |
| Structure | Pooled investment scheme | Individually managed portfolio | Privately pooled investment vehicle |
| General minimum | Scheme-specific; often accessible with small amounts | ₹50 lakh for new clients | Generally ₹1 crore |
| Portfolio ownership | Units of the scheme | Direct ownership of underlying securities, subject to structure | Units or interests in the fund |
| Customisation | Limited to available schemes | Greater scope for individual portfolio management | Depends on the fund's mandate |
| Investment approach | Equity, debt, hybrid, index and other categories | Strategy-specific managed portfolios | Private equity, credit, venture capital, listed securities and other alternatives |
| Liquidity | Depends on scheme type and exit terms | Depends on portfolio holdings and agreement | Depends on category, scheme and redemption terms |
| Suitable for | Investors seeking accessible, diversified market exposure | Investors seeking a managed individual portfolio | Investors seeking specialised strategies and able to accept the associated risks |
Mutual funds
NRI investment in mutual funds is permitted in India, subject to the mutual fund scheme's offer documents and applicable regulations. NRIs can consider equity, debt, hybrid, index and other available schemes.
Mutual funds are often a practical starting point because they offer diversified exposure without requiring the investor to select and manage every security directly.
The answer to can NRI invest in mutual funds in India is generally yes. However, some fund houses restrict or apply additional procedures to investors residing in particular countries, especially the United States and Canada.
Portfolio Management Services
PMS offers a more tailored investment arrangement. The portfolio manager manages the client's portfolio according to an agreed strategy and mandate.
It may suit investors who want a defined investment approach, individual security ownership and a larger allocation to a particular manager's strategy. However, portfolio concentration, charges, turnover and liquidity need careful assessment.
Explore Portfolio Management Services in India to understand the different PMS strategies available.
Alternative Investment Funds
AIFs pool capital from eligible investors and invest according to a defined fund strategy. The three broad categories have different mandates:
- Category I: Includes venture capital, SME, infrastructure and other specified funds.
- Category II: Includes private equity, debt and other funds that do not fall under Category I or III.
- Category III: Includes funds using complex or diverse strategies, including long-short and certain trading approaches. They may use leverage as permitted by regulations.
AIFs can involve longer holding periods, limited redemption opportunities and greater complexity. They are not simply higher-minimum mutual funds.
Explore Alternative Investment Funds (AIFs) to compare strategies across categories.
Specialised Investment Funds
Specialised Investment Funds (SIFs) are a SEBI-regulated investment structure within the mutual fund framework. They allow eligible mutual fund houses to offer investment strategies with additional flexibility compared with conventional mutual fund schemes.
SIF strategies may include specialised equity, debt and hybrid approaches, subject to the applicable framework and scheme documents.
The general minimum investment threshold is ₹10 lakh across SIF investment strategies, subject to applicable exceptions and conditions.
NRIs should confirm whether a particular SIF accepts investors from their country of residence and review its investment strategy, minimum subscription, redemption terms and risk disclosures.
Explore Special Investment Funds to understand the structure and available strategies.
GIFT City Investment Options for NRIs
GIFT City, or Gujarat International Finance Tec-City, hosts India's International Financial Services Centre (IFSC). The IFSC operates under the regulatory framework of the International Financial Services Centres Authority (IFSCA).
Eligible NRIs and other non-resident investors can evaluate investment structures offered through IFSC-registered entities. Depending on the fund and its mandate, these structures may provide access to Indian and international investment exposure.
Key considerations include:
- Currency denomination: Some GIFT City funds accept subscriptions and make transactions in foreign currencies, subject to the fund's terms.
- Investment structure: Funds may operate under the applicable IFSCA fund-management framework.
- Investment strategy: Offerings may include equity, debt, fund-of-funds and other eligible strategies.
- Eligibility: Investor eligibility and onboarding requirements depend on the specific fund and jurisdiction.
- Tax treatment: Tax outcomes depend on the investment vehicle, investor status, income type and applicable law.
- Liquidity: Subscription, redemption and exit conditions are defined by the relevant fund documents.
GIFT City funds should not automatically be treated as equivalent to domestic mutual funds, PMS or SEBI-registered AIFs. Their regulatory framework, currency arrangements and investment structures can differ.
NRIs should compare the fund's jurisdiction, regulatory status, minimum investment, fees, currency exposure, tax treatment and redemption terms before investing.
Read ALTPORT's guides on GIFT City funds, how NRIs and foreign investors can access AIFs through GIFT City and GIFT City funds for NRI investment.
How Do Investment Goals, Liquidity and Risk Tolerance Affect NRI Decisions?
The same investment may suit one NRI and be unsuitable for another. A useful comparison begins with the purpose of the money.
| Investment Goal | Options to Evaluate | Key Consideration |
| Capital preservation | NRE/FCNR(B) deposits, eligible government securities | Credit risk, interest rates and currency exposure |
| Regular income | Deposits, selected debt products, eligible bonds | Taxation, payout terms and reinvestment risk |
| Long-term growth | Equity mutual funds, direct stocks, PMS | Market volatility and investment horizon |
| Retirement planning | NPS, diversified mutual funds and suitable long-term products | Withdrawal rules and retirement location |
| Alternative exposure | AIFs across eligible categories | Liquidity, valuation and manager risk |
| Property ownership | Eligible residential or commercial property | Legal title, rental yield and exit liquidity |
Match the investment to the time horizon
Money needed within one or two years should generally not be exposed to highly volatile or illiquid strategies. Equity-oriented investments are usually evaluated over longer periods, while AIFs may have scheme-specific lock-ins or redemption restrictions.
Understand liquidity before investing
Liquidity is not the same as the ability to sell an asset eventually. It refers to how quickly an investor can access money without accepting a substantial discount or facing restrictive exit conditions.
For example, an open-ended mutual fund may offer regular redemption subject to its terms. A close-ended AIF may require the investor to remain invested until the scheme's maturity or permitted exit event.
Consider currency exposure
An investor earning and spending in US dollars, pounds or dirhams should consider the effect of exchange-rate movement on rupee-denominated returns.
Even when an Indian investment generates a positive return in INR, the value measured in the investor's home currency can differ. Currency exposure should therefore form part of the portfolio comparison.
What Due-Diligence Checks Should NRIs Complete Before Investing?
A product's return history is only one part of its evaluation. Before committing funds, NRIs should examine the investment structure, manager, costs and exit conditions.
Regulatory and legal checks
- Confirm that the relevant fund, portfolio manager, intermediary or institution has the required registration or authorisation.
- Read the offer document, placement memorandum or PMS disclosure document.
- Understand the investor eligibility conditions and permitted funding route.
- Check whether the product accepts investors from the country where the NRI resides.
Investment and portfolio checks
- Understand the investment objective and strategy.
- Review portfolio concentration, asset allocation and sector exposure.
- Examine the benchmark and the method used to report performance.
- Compare performance across suitable market cycles rather than relying on one strong period.
- Review the fund manager's experience and investment process.
Cost and liquidity checks
- Identify management fees, performance-linked fees and other expenses.
- Understand exit loads, lock-ins, redemption windows and transfer restrictions.
- Check how unlisted or illiquid holdings are valued.
- Understand the process for receiving redemption proceeds and repatriating funds.
Tax and documentation checks
- Complete PAN and applicable KYC requirements.
- Provide FATCA/CRS declarations and tax residency details.
- Understand TDS and Indian income-tax reporting.
- Assess whether DTAA relief may apply in the country of residence.
- Maintain records of remittances, investment cost, tax deductions and sale proceeds.
These checks help make NRI investment in India more systematic and reduce the likelihood of choosing a product based only on marketing material or recent returns.
What Investment Restrictions Should NRIs Know About?
NRIs have access to several Indian investment routes, but certain restrictions apply.
Mutual funds and stocks
NRIs can invest in domestic mutual funds, subject to scheme-specific eligibility and documentation. Direct investment in Indian shares is also permitted under applicable FEMA provisions and the Portfolio Investment Scheme (PIS), where relevant.
The permitted route depends on the security, account type and repatriation basis. NRIs should confirm the trading, demat and bank-account requirements with their authorised intermediary.
Real estate
NRIs and OCIs can generally purchase residential and commercial property in India. They cannot purchase agricultural land, plantation property or farmhouses under the general permission available to them.
Payment must follow permitted banking channels and non-resident account rules.
PPF and NPS
NRIs cannot open a new Public Provident Fund (PPF) account. An existing PPF account opened while resident may generally continue until maturity under the applicable rules, but fresh extensions and contributions are subject to the relevant conditions.
Eligible NRIs and OCIs can subscribe to the National Pension System (NPS) under the applicable framework. NPS is market-linked, and its withdrawal and annuity rules should be considered before investing.
Country-specific restrictions
A financial institution may have additional onboarding or reporting requirements for investors residing in certain jurisdictions. This is particularly relevant when evaluating mutual funds, PMS and AIFs from the United States, Canada and other countries with specific compliance frameworks.
Where Can NRIs Verify Investment Rules and Eligibility?
The rules governing NRI investment in India come from multiple regulators and institutions. The following official resources are useful starting points:
| Authority | What to Check |
| Reserve Bank of India (RBI) | NRE, NRO and FCNR(B) accounts, repatriation, FEMA and investment routes |
| Securities and Exchange Board of India (SEBI) | PMS regulations, AIF regulations and market-related investment requirements |
| Association of Mutual Funds in India (AMFI) | Mutual fund investor information and NRI eligibility guidance |
| National Stock Exchange (NSE) | NRI trading and investment procedures |
| Pension Fund Regulatory and Development Authority (PFRDA) | NPS eligibility, account rules and withdrawals |
| Income Tax Department | Indian tax obligations, non-resident taxation and treaty-related relief |
NRIs should also consult their authorised dealer bank, investment provider and tax adviser for transaction-specific requirements. A rule that applies to one investment route may not apply to another.
Key Takeaways for NRIs Evaluating Investment Options in India
The right NRI investment in India depends on more than the amount available to invest. Account type, source of funds, repatriation needs, tax residency, investment horizon and risk tolerance all influence the decision.
- Below ₹50 lakh, deposits, mutual funds and eligible securities may offer accessible starting points.
- From ₹50 lakh, PMS becomes an option to evaluate, subject to suitability.
- From ₹1 crore, eligible investors can consider AIFs, while accounting for their liquidity and strategy risks.
- Larger portfolios may benefit from coordinated allocations across Indian and overseas assets.
- NRE, NRO and FCNR(B) accounts serve different purposes and should not be treated as interchangeable.
- Past returns alone are not enough to judge an investment. Costs, manager quality, liquidity and downside risk matter.
A well-planned portfolio should complement the investor's global financial position rather than duplicate exposures already held overseas.
Explore NRI Investment Opportunities with ALTPORT
NRIs evaluating PMS, AIFs, GIFT City funds and other investment strategies can explore the investment options available through ALTPORT.
ALTPORT provides access to investment opportunities across Category I, II and III AIFs, PMS, GIFT City funds and other eligible investment products. As a distributor, ALTPORT helps investors explore and compare available opportunities based on their investment objectives, time horizon, liquidity requirements and risk considerations.
Explore AIF investment options, PMS strategies, PMS for NRIs and GIFT City funds to understand their mandates, investment approaches and associated risks.
You can also visit the ALTPORT NRI Corner for additional information on NRI investment structures, eligibility and regulatory considerations.
Disclaimer
This article is intended for general informational and educational purposes. It does not constitute investment, legal, tax or financial advice, or a recommendation to buy or sell any security or investment product. Investment eligibility, taxation, repatriation and regulatory requirements depend on the investor's residential status, country of residence, source of funds and applicable laws. Market-linked investments carry risk, and returns are not guaranteed. Investors should read the relevant offer documents and consult qualified financial, legal and tax professionals before making investment decisions.