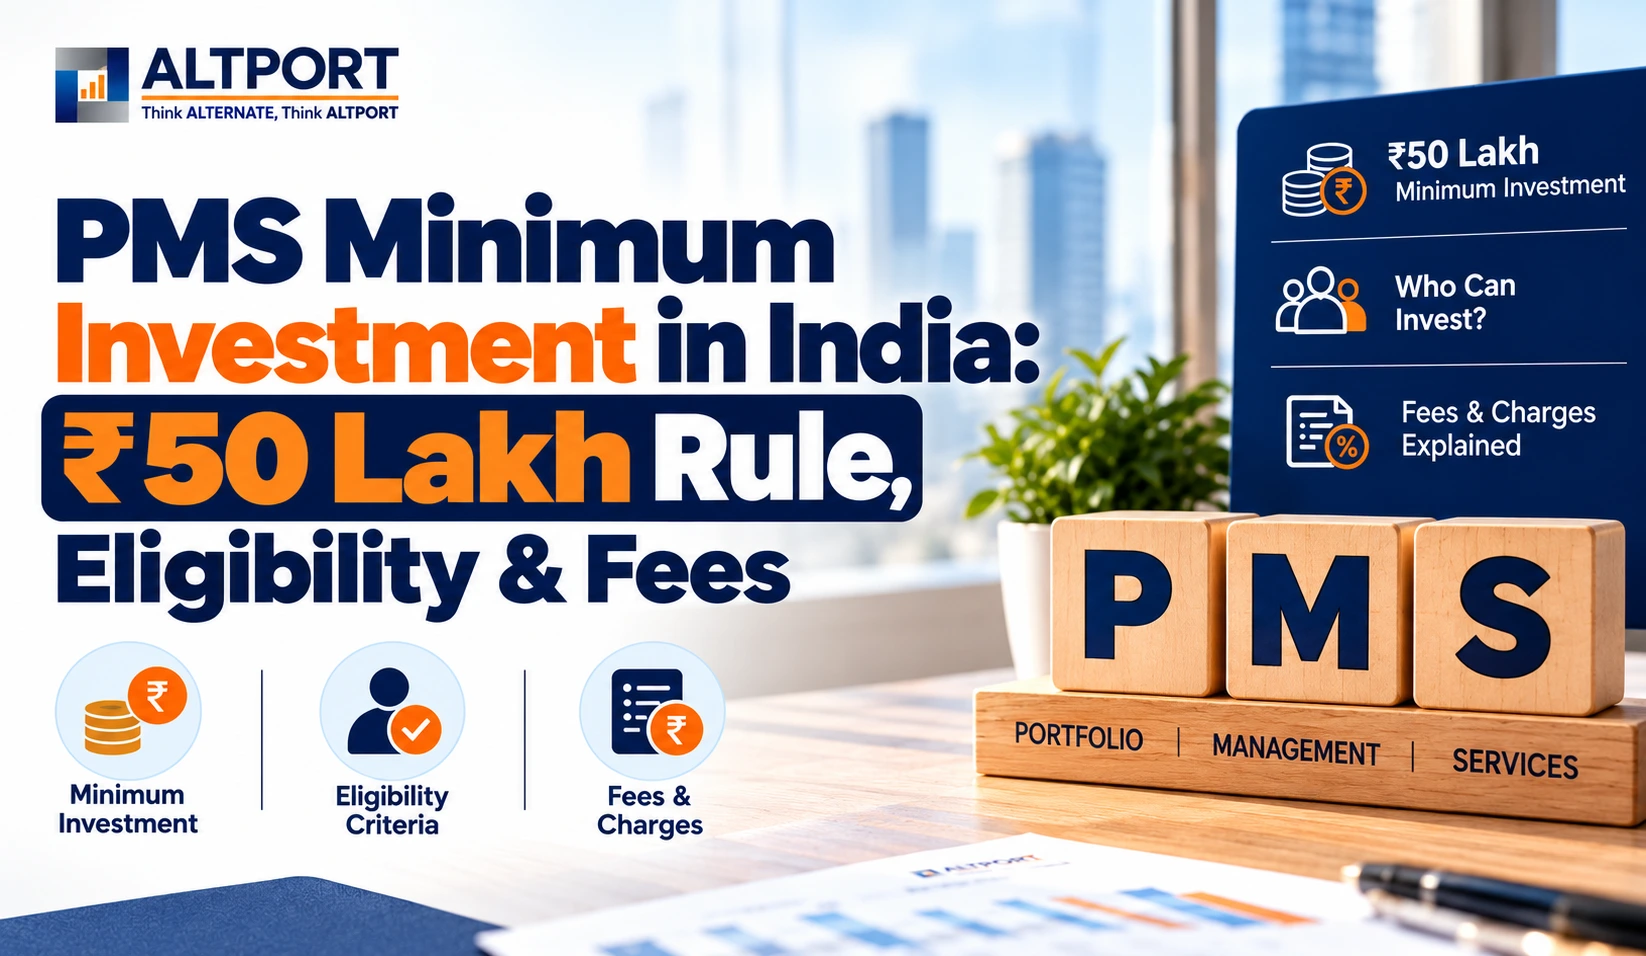
The PMS minimum investment in India is ₹50 lakh per client for conventional portfolio management services under SEBI rules (as of October 2026). You can invest it as cash, eligible securities or a mix of both.
This regulatory minimum is separate from the fees a portfolio manager charges. It is also separate from any higher minimum a particular strategy may set. Before you allocate capital, understand the eligibility rules, the costs, the withdrawal limits and the exceptions, including the new ₹25 lakh PRIM route that starts on 1 April 2027.
What Is the Minimum Investment for PMS in India?
The minimum investment for conventional PMS in India is ₹50 lakh, set by Regulation 23(2) of the SEBI (Portfolio Managers) Regulations, 2020. SEBI’s Master Circular adds that the client’s first single lump-sum investment must be at least ₹50 lakh. You cannot build up to it through smaller instalments.
Investors should distinguish between three amounts:
- SEBI’s regulatory minimum: ₹50 lakh for conventional PMS. This is the PMS minimum amount the law requires.
- Strategy-specific minimum: a portfolio manager may require more for a particular investment approach.
- Fees and expenses: management fees, performance fees and other charges are paid on top of the invested principal, not out of the ₹50 lakh.
For the official position, see the SEBI Portfolio Managers FAQs and the SEBI Master Circular for Portfolio Managers. For a broader explanation of how the service works, read ALTPORT’s guide to Portfolio Management Services in India.
Why Does PMS Require a Minimum Investment of ₹50 Lakh?
SEBI raised the PMS minimum from ₹25 lakh to ₹50 lakh in January 2020. The aim was to limit PMS to investors who can absorb the risks of a concentrated, individually managed portfolio.
Unlike a mutual fund, conventional PMS does not pool your money with other investors. The portfolio manager runs your own portfolio under an agreed mandate. These portfolios can be concentrated and volatile, and they can lose money. A higher entry threshold helps ensure that PMS clients have the financial capacity for that risk.
Meeting the minimum does not make a strategy suitable for you. Before investing, review the manager’s investment approach, disclosure document, fee structure and client agreement.
Can You Invest Less Than ₹50 Lakh in PMS?
No. A new conventional PMS account requires at least ₹50 lakh. There are three exceptions:
- Accredited investors: investors certified as accredited under SEBI’s framework are exempt from the minimum. Being an HNI does not by itself make you an accredited investor; you need formal accreditation.
- Co-investment PMS: co-investment portfolio managers are exempt, subject to their own conditions.
- PRIM route (from 1 April 2027): a separate PMS route for mutual fund portfolios with a ₹25 lakh minimum, explained in the section on 2027 changes below.
Existing clients: clients who joined before 21 January 2020, when the minimum was ₹25 lakh, must bring any further investment up to the ₹50 lakh floor. Under the new 2026 Regulations, these clients must top up to ₹50 lakh within 12 months from 1 April 2027.
If you have less than ₹50 lakh and want an actively managed strategy, a Specialised Investment Fund (SIF) starts at ₹10 lakh. See ALTPORT’s SIF vs PMS vs AIF comparison to understand the trade-offs.
Does the ₹50 Lakh PMS Minimum Apply to Each Portfolio Manager?
Yes. Each conventional PMS provider must receive at least ₹50 lakh from you. You cannot combine amounts spread across providers to meet the minimum.
For example, splitting ₹50 lakh into ₹25 lakh with each of two providers leaves both accounts below the minimum. With ₹1 crore, you could open two separate ₹50 lakh accounts, provided both providers accept you.
Within a single provider that offers several strategies, each strategy does not automatically need its own ₹50 lakh. Ask the manager how your client agreement treats investments across its different approaches.
What Happens If Your PMS Portfolio Falls Below ₹50 Lakh?
You do not need to top up if the portfolio falls below ₹50 lakh because of market movements. SEBI’s FAQs confirm that a fall in value alone does not trigger a top-up.
A partial withdrawal is treated differently. You can withdraw part of your portfolio under the terms of your agreement, but the remaining value must stay at or above ₹50 lakh. A passive fall caused by the market is acceptable; a withdrawal that takes you below the floor is not.
PMS also has no lock-in period. SEBI does not allow portfolio managers to impose one, although they can charge exit fees for early exit if the agreement provides for them.
Who Is Eligible to Invest in PMS in India?
Resident Indian individuals, NRIs, companies, LLPs, HUFs, trusts and partnership firms can invest in PMS. Each must meet KYC requirements and the portfolio manager’s onboarding checks.
- Resident individuals: must meet the investment minimum and documentation requirements.
- NRIs: must also comply with banking, FEMA and tax requirements.
- Companies and LLPs: invest through authorised signatories, with board or partner approval.
- HUFs, trusts and partnership firms: eligible if their legal structure and constitution allow them to invest.
Having enough capital is not the only test. The manager will also verify your identity, source of funds, legal structure, bank details and tax status.
What Is the PMS Minimum Investment for NRIs?
The PMS minimum investment for NRIs is ₹50 lakh, the same as for resident investors, and the same exceptions apply. Before investing, NRIs should confirm with the portfolio manager:
- the account type to use (NRE or NRO)
- how the investment will be funded
- how repatriation will work
For account setup, taxation and repatriation, read ALTPORT’s guide to PMS for NRIs in India. For the full onboarding process, see the NRI guide to investing in PMS and AIFs from abroad.
What Additional Costs Should PMS Investors Consider?
The ₹50 lakh is the capital invested in your portfolio. Fees are charged separately on top of it. Depending on your agreement, you may pay:
| Cost component | What to check |
|---|---|
| Management fee | Rate, calculation basis and billing frequency |
| Performance-linked fee | Calculation method, hurdle rate and high-water mark |
| Brokerage and transaction costs | Trading-related and statutory expenses |
| Custody and demat charges | Costs of holding and administering securities |
| Other permitted expenses | Administration and other expenses specified in the agreement |
| GST | Whether it is included in the quoted fee |
| Exit charges | Exit fees and the period they apply |
Ask the manager for a complete written breakdown of costs instead of comparing only the headline management fee. To see how fees differ between providers, check ALTPORT’s fee snapshot of India’s top PMS strategies.
How Do PMS Fees Work?
PMS fees are set in your client agreement as a fixed fee, a performance-linked fee or a combination of the two. SEBI prohibits portfolio managers from charging upfront fees, directly or indirectly.
Performance-linked fees usually apply only above a hurdle rate. Many also use a high-water mark, so you do not pay a performance fee twice for recovering the same losses. The agreement must disclose every fee and how it is calculated. Read it in full before signing.
PMS vs Mutual Funds vs AIFs: Minimum Investment Compared
Mutual funds can start from a few hundred rupees. Conventional PMS starts at ₹50 lakh, and AIFs generally start at ₹1 crore.
| Feature | Mutual funds | Conventional PMS | AIFs |
|---|---|---|---|
| Minimum investment | Scheme-specific, often ₹100–₹5,000 | ₹50 lakh | Generally ₹1 crore |
| Structure | Pooled scheme | Individually managed portfolio | Pooled fund |
| Ownership | Mutual fund units | Direct ownership of securities | Fund units |
| Lock-in | Usually none (ELSS: 3 years) | None; exit fees may apply | Varies by category and fund term |
| Accredited investor exemption | Not applicable | Yes | Yes |
A higher minimum does not make PMS a better choice than a mutual fund or an AIF. The right choice depends on your objectives, risk tolerance, liquidity needs and costs. For a deeper comparison, read ALTPORT’s guides to PMS vs mutual funds and the full mutual fund vs PMS vs AIF comparison. If you are considering an AIF, see how HNIs compare AIFs across categories.
What Changes From 1 April 2027? The New PRIM Route
The conventional PMS minimum stays at ₹50 lakh. The SEBI (Portfolio Managers) Regulations, 2026 were notified in October 2026 and take effect on 1 April 2027, replacing the 2020 rules. They add a new ₹25 lakh route called PRIM (Portfolio Management Service Route for Investment in Mutual Fund units).
Key features of PRIM:
- Minimum investment: ₹25 lakh per client.
- What it can hold: only direct plans of mutual funds, including index funds, ETFs and SIFs. It cannot hold shares or bonds directly.
- Fee cap: the fixed fee is capped at 1% of client AUM. A performance-linked fee is also allowed.
- Concentration limit: no more than 25% can be invested in schemes of the manager’s own group or associate AMCs.
- Who can offer it: existing PMS firms, as a separate investment approach, or new PRIM-only licence holders.
Two other changes matter for investors. Clients who joined before 2020 with less than ₹50 lakh must top up to ₹50 lakh within 12 months from 1 April 2027. Conventional PMS will also be allowed to invest in IPOs, new debt issues and a wider range of foreign securities.
How to Decide Whether PMS Is Suitable for Your Investment Goals
PMS suits investors who can commit at least ₹50 lakh for several years and can absorb losses from a concentrated portfolio. Before choosing a provider, assess:
- Investment horizon: whether the capital can stay invested through market cycles.
- Risk capacity: potential losses, portfolio concentration and the strategy’s risk profile.
- Portfolio allocation: what share of your total investable wealth goes into PMS.
- Investment approach: the manager’s process, investment universe and risk controls.
- Total costs: fixed fees, performance fees and all other expenses.
- Liquidity: exit fees, and how partial withdrawals interact with the ₹50 lakh floor.
- Due diligence: SEBI registration, the disclosure document, track record and the agreement terms.
For a seven-question due-diligence checklist, read ALTPORT’s guide on how to select a PMS provider in India. To compare managers’ processes and track records, see top PMS fund managers in India.
Conclusion
The PMS minimum investment in India is ₹50 lakh for conventional PMS. The exceptions are accredited investors, co-investment PMS and, from 1 April 2027, the ₹25 lakh PRIM route for mutual fund portfolios. Keep this regulatory floor separate in your mind from a strategy’s own higher minimum and from the fees you will pay on top.
Before investing, check your eligibility, total costs, the investment strategy, the risks and the withdrawal terms. Review the disclosure document and client agreement in full. When you are ready to shortlist, explore PMS strategies on ALTPORT.
Disclaimer: This article is for general educational purposes only and does not constitute investment, legal or tax advice. PMS investments are subject to market risks, including the possible loss of capital. Minimum-investment provisions, exemptions and fees are subject to SEBI regulations and contractual terms, which may change. Verify the current requirements and review the relevant disclosure documents before investing.