An alternative investment fund may have a well-defined investment strategy, an attractive track record and a strong portfolio. But what happens when the person responsible for its investment decisions suddenly leaves?
For investors in Alternative Investment Funds (AIFs) and Portfolio Management Services (PMS), the experience and continuity of the investment team matter. A fund's performance may depend heavily on the investment manager, Chief Investment Officer (CIO), founding partner or a small group of senior professionals.
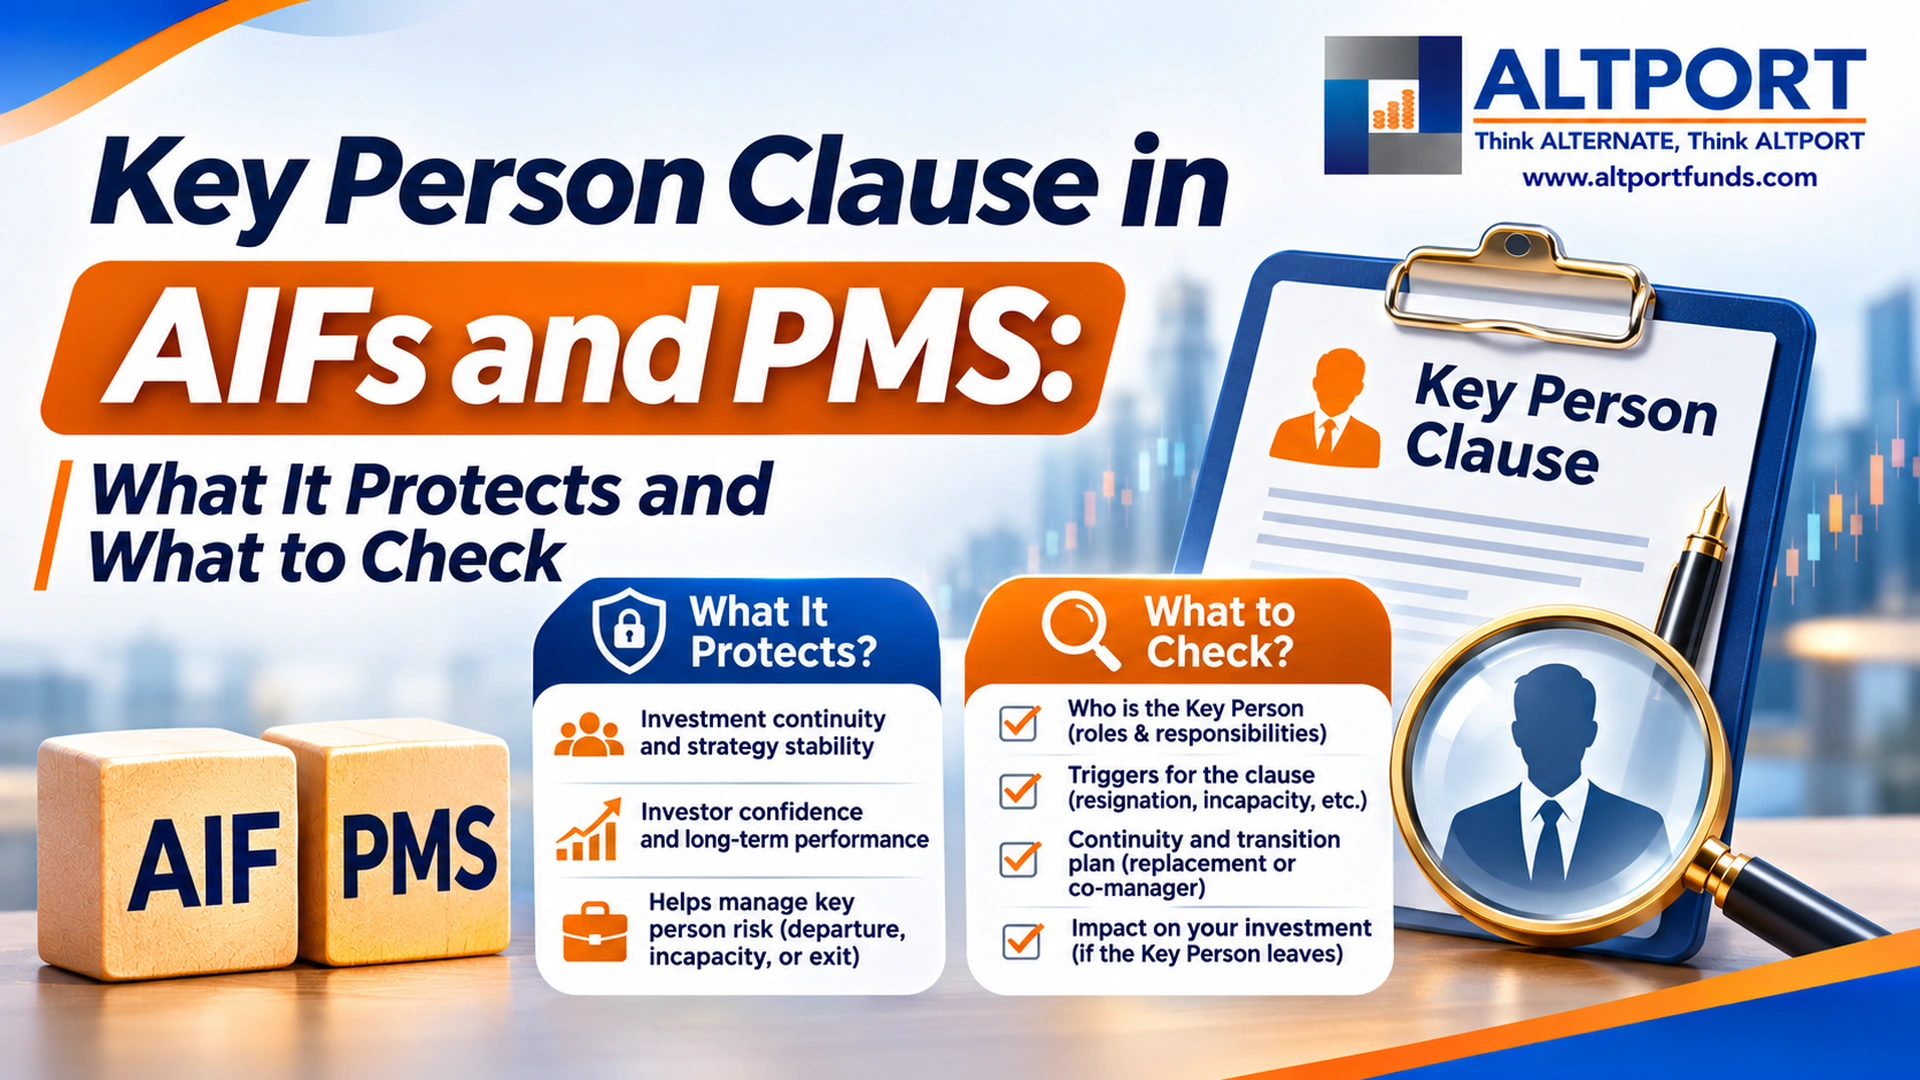
This is where the key person clause in AIF documentation becomes important. It addresses the risks associated with the departure, incapacity or unavailability of individuals whose involvement is considered critical to the fund.
Understanding the key person clause in AIF structures helps investors assess management continuity, governance quality and the protection available when an important investment professional leaves.
However, not every fund offers the same protection. Investors must examine the actual contractual provisions rather than assume that every AIF follows an identical process.
Investors evaluating alternative investment opportunities should also understand the broader process of AIF and PMS manager due diligence, including investment team experience, succession planning, governance and fund documentation.
What Is a Key Person Clause in an AIF?
The key person clause meaning is a contractual provision that identifies individuals whose continued involvement is considered essential to managing an investment fund.
These individuals are commonly called key persons. Depending on the fund, they may include:
- Founder or Managing Partner
- Chief Investment Officer (CIO)
- Fund Manager
- Head of Investments
- Senior Portfolio Managers
- Investment Committee members
- Other professionals responsible for critical investment decisions
The key person clause in AIF documentation establishes what happens if one or more identified individuals become unavailable or leave the fund.
For example, consider a Category II AIF managed by a team of three senior investment professionals. The fund's strategy, investment sourcing and portfolio decisions depend heavily on these individuals.
If the CIO and one senior investment professional leave during the investment period, the fund may face a significant management disruption.
A properly drafted key person clause in AIF documentation can address this situation through predefined procedures.
These may include:
- Temporarily suspending fresh investments.
- Restricting new capital deployment.
- Notifying investors about the event.
- Allowing investors to participate in decisions regarding the replacement.
- Requiring approval for appointing a successor.
- Resuming investment activities after specified conditions are fulfilled.
The actual provisions depend on the fund's Private Placement Memorandum (PPM), contribution agreement and other governing documents.
For a better understanding of investment terminology, fund structures and contractual concepts, investors can also refer to our AIF and PMS investment glossary.
Key Person Clause Explained Through an Example
Suppose an AIF identifies its founding partner and CIO as its two key persons.
Its PPM states that if both individuals cease to devote the required time to the fund, a key person event will occur.
The agreement further provides that fresh investments will be suspended until a replacement is appointed and approved through the specified process.
If both professionals leave, the fund cannot simply continue deploying committed capital as usual. It must follow the contractual procedures.
This is the practical purpose of the key person clause in AIF structures: protecting investors against excessive dependence on a few individuals.
Why Key Person Risk Matters to AIF Investors
An investment manager's experience, decision-making ability and investment philosophy can influence a fund's long-term performance.
This is particularly relevant for private equity, venture capital, private credit and other strategies where investment sourcing, due diligence and portfolio monitoring require specialised expertise.
Key person risk in AIF investments arises when a fund depends heavily on specific individuals rather than an established investment process supported by a broader team.
Consider these potential risks:
| Risk | Possible impact on investors |
| Fund manager departure | Disruption in investment decisions |
| Loss of institutional knowledge | Reduced understanding of existing portfolio companies |
| Investment philosophy changes | Departure from the original investment strategy |
| Weak succession planning | Delays in appointing replacements |
| Team conflicts | Uncertainty around decision-making authority |
| Concentrated expertise | Excessive dependence on a few professionals |
| Leadership transition | Potential delays in sourcing and executing investments |
Why Is This Important for Private Equity Funds?
The key man clause private equity concept has particular importance because private equity investments often involve long holding periods and active portfolio management.
Fund managers may spend years sourcing opportunities, negotiating transactions, working with portfolio companies and planning exits.
When a founding partner or lead investment professional leaves, the impact can extend beyond daily fund operations.
For example, the departing professional may have established relationships with promoters, industry specialists and potential acquisition targets.
Replacing that individual does not automatically replace those relationships or the investment experience accumulated over several years.
A key person clause private equity fund provision can help establish what happens when such an individual becomes unavailable.
The key person clause in AIF framework therefore serves as an important governance safeguard, particularly in funds where investment decisions depend on a small leadership team.
Connection Between Key Person Risk and Fund Performance
Investors should not assume that a fund's historical returns will continue after a leadership change.
An AIF manager's track record may reflect the contribution of specific individuals. If those professionals leave, the investment process and decision-making quality may change.
During AIF investment due diligence, investors should examine:
- Who generated the fund's historical investment returns?
- Are those individuals still associated with the fund?
- Does the wider team have comparable experience?
- Are investment decisions dependent on one individual?
- Is there a documented succession plan?
The key person clause in AIF documents should complement these checks rather than replace them.
What Can Trigger a Key Person Event?
A key person event in AIF structures occurs when a specified condition involving an identified key person is triggered.
The exact conditions differ across funds. There is no single universal trigger applicable to every AIF.
Common triggering events include:
- Resignation or departure
A key person resigns, retires or leaves the investment manager.
- Death or permanent incapacity
An identified individual becomes permanently unable to perform their responsibilities.
- Extended absence
A key person remains unavailable beyond the period permitted under the fund documents.
- Loss of involvement
The individual no longer devotes the agreed amount of professional time to managing the fund.
- Change in investment responsibilities
The individual is reassigned to another business or investment strategy, reducing their involvement in the existing fund.
- Departure of multiple investment professionals
A specified number or proportion of the identified investment team members leave within a defined period.
Not every departure automatically creates a key person event. For instance, the resignation of a junior analyst may not trigger the provision.
A well-drafted key person clause in AIF documentation should clearly identify the relevant individuals and the conditions that constitute an event.
Investors should particularly examine whether the clause covers one individual or requires multiple key persons to become unavailable.
They should also check whether temporary absence, resignation and permanent departure are treated differently.
What Happens When a Key Person Leaves the Fund?
The consequences depend on the contractual terms of the AIF.
A key person event does not automatically mean that the fund closes, liquidates its investments or returns investor capital.
Instead, the fund follows the procedures specified in its governing documents.
The common consequences include:
| Consequence | What it means for investors |
| Investor notification | Investors receive information about the departure |
| Investment suspension | Fresh investments may be temporarily restricted |
| Capital deployment restrictions | Uncalled commitments may not be deployed for new investments |
| Replacement process | The manager initiates a successor appointment |
| Investor approval | Consent may be required under specified circumstances |
| Investment committee review | Existing investment decisions may require additional oversight |
| Resumption of operations | Investment activities resume after contractual conditions are satisfied |
Key Person Suspension Clause
A key person suspension clause determines whether the fund must temporarily stop making fresh investments after a triggering event.
For example, an AIF may suspend new investments until the manager appoints a suitable replacement and completes the required approval process.
However, suspension does not necessarily stop all fund activities.
Depending on the PPM, the manager may continue:
- Managing existing portfolio investments.
- Monitoring portfolio companies.
- Meeting contractual payment obligations.
- Completing transactions already approved or committed.
- Handling exits and distributions.
- Managing administrative and regulatory responsibilities.
Investors should distinguish between suspending new investments and suspending the entire fund.
Fund Manager Replacement Process
The replacement process is another important part of the key person clause in AIF framework.
Investors should understand whether the manager can appoint a successor independently or needs investor consent.
A well-defined process should address:
- Eligibility and experience requirements for the replacement.
- Approval authority and voting thresholds.
- Investor consultation or consent requirements.
- Time limits for appointing the successor.
- Procedures if the replacement is not approved.
- Conditions for restarting investment activities.
The key person event consequences can vary significantly depending on these provisions.
Some funds may provide a clear replacement mechanism. Others may leave considerable discretion with the investment manager.
Investors should also examine what happens if the manager cannot appoint an acceptable replacement within the specified period.
Key Person Clauses in AIFs vs PMS Agreements
The key person clause in AIF structures and PMS agreements serve a similar purpose: addressing the risks associated with dependence on important investment professionals.
However, their legal and operational frameworks are different.
An AIF is a pooled investment vehicle, whereas PMS manages a client's portfolio under an individual agreement.
| Comparison factor | AIF | PMS |
| Investment structure | Pooled investment vehicle | Individual client portfolio |
| Governing documents | PPM, contribution agreement and fund documents | PMS agreement and disclosure documents |
| Key person identification | Generally disclosed through fund documentation | Depends on the investment manager's disclosures and agreement |
| Regulatory framework | SEBI AIF Regulations, 2012 | SEBI Portfolio Managers Regulations, 2020 |
| Departure implications | May trigger fund-level restrictions or suspension | May affect the investment approach and client relationship |
| Replacement | Governed by fund documents | Governed by applicable agreements and regulatory requirements |
| Investor rights | Based on fund documents and applicable regulations | Based on the individual client agreement and applicable regulations |
Is a Key Person Clause Mandatory in PMS?
The key person clause in PMS arrangements requires a slightly different interpretation.
SEBI's Portfolio Managers Regulations, 2020 require a written agreement between the portfolio manager and client.
Regulation 22 and Schedule IV specify the minimum matters that the agreement should address.
These include investment objectives, services, investment approach, risk factors, termination provisions, withdrawal conditions, custody, reporting and other contractual obligations.
However, the regulations do not prescribe one standard key-person event clause for every PMS agreement.
Therefore, investors should check whether their agreement or related disclosures identify the key investment professionals and explain the consequences of their departure.
For discretionary PMS, this is particularly relevant because the portfolio manager exercises investment discretion within the agreed mandate.
A change in the investment leadership team may affect the investment philosophy, portfolio construction and execution approach.
What Investors Should Check in the PPM or PMS Agreement
The AIF private placement memorandum is one of the most important documents for understanding a fund's management structure.
SEBI requires AIFs to disclose material information about the fund and manager, including the background of the key investment team.
The prescribed PPM framework also covers investment strategy, risk factors, fees, expenses, service providers, governance and other relevant information.
For a detailed explanation of fund disclosures, fees, investment strategy and investor rights, read our guide to the AIF private placement memorandum (PPM).
Investors should examine the following provisions carefully.
- Identification of key persons
Check whether the fund clearly identifies its key investment professionals.
SEBI's AIF framework requires disclosure of key management personnel in the PPM. This includes members of the key investment team and other specified decision-makers.
- Definition of a key person event
The AIF PPM clauses should clearly explain what constitutes a triggering event.
Check whether the clause covers resignation, retirement, death, incapacity, extended absence or reduced involvement.
- Minimum number of key persons
Some funds may require a specified number of identified professionals to remain actively involved.
Understand whether the departure of one person is sufficient to trigger restrictions or whether multiple departures are necessary.
- Investment suspension conditions
Check whether fresh investments are automatically suspended after an event.
Also examine whether the manager can continue making investments already approved or contractually committed.
- Replacement and approval rights
The key person clause in AIF documents should explain how replacements are selected and approved.
Check whether investors have voting rights and whether a minimum approval threshold applies.
- Time limits
Look for the period within which the manager must appoint a replacement.
Also check what happens if the required replacement is not appointed within that period.
- Investor communication
Understand how quickly investors will be informed about a departure and what information they will receive.
SEBI's framework requires changes in disclosed key management personnel to be intimated to investors and the regulator.
- Consequences of an unresolved event
Check whether an unresolved event can result in extended investment suspension, changes to the investment period or other contractual remedies.
Do not assume that a key person event automatically gives investors an exit or redemption right.
- Investment committee responsibilities
Examine the role of the AIF investment committee, its composition and decision-making authority.
Understand whether it can approve replacements, investment decisions or changes to the fund's operating arrangements.
- Succession planning
Ask whether the manager has identified internal successors and whether investment responsibilities are distributed across a broader team.
The key person clause in AIF documentation should be assessed alongside the manager's actual succession planning capabilities.
What Does SEBI Require Regarding Key Management Personnel?
SEBI's AIF framework provides an important governance foundation.
Under Regulation 20 and the related regulatory provisions, key management personnel are subject to the applicable code of conduct.
SEBI's June 2021 circular and subsequent master circular provisions clarify the scope of key management personnel.
These include:
- Members of the manager's key investment team disclosed in the PPM.
- Senior decision-makers, including the MD, CEO, CIO and Whole-Time Directors or equivalent positions.
- Other individuals designated as key management personnel by the AIF or manager.
The names of these individuals must be disclosed in the PPM. Changes must be communicated to investors and SEBI.
Additionally, since May 10, 2024, at least one key person in the manager's key investment team must meet the specified NISM certification requirement under Regulation 4(g)(i), subject to the applicable implementation provisions.
This requirement reinforces the importance of professional competence within the investment team.
However, regulatory disclosure and a contractual key-person protection are two different things. Investors should not confuse mandatory disclosure with an automatic suspension or replacement right.
Investors should also understand the wider AIF and PMS regulatory framework before evaluating the responsibilities of fund managers and investment professionals.
Key Person Due-Diligence Checklist Before Investing
AIF manager due diligence should go beyond examining historical returns and the fund's investment strategy.
The key person clause in AIF documentation deserves particular attention because it explains how the fund responds to management disruptions.
Understanding how to choose the right AIF in India involves examining the fund manager's experience, investment strategy, governance, fees and contractual protections.
Use this checklist before committing capital.
| Due-diligence area | What investors should examine |
| Key investment team | Names, roles and experience of identified professionals |
| Manager track record | Individual contribution to historical performance |
| Key person definition | Clarity around identified individuals |
| Trigger conditions | Events that activate the provision |
| Suspension rights | Whether fresh investments are restricted |
| Replacement process | Appointment criteria and approval authority |
| Investor rights | Voting, consent and communication provisions |
| Time limits | Deadline for appointing a successor |
| Succession planning | Availability of experienced internal replacements |
| Investment committee | Composition, authority and decision-making process |
| Team stability | Historical departures and leadership changes |
| Unresolved events | Consequences if a suitable replacement is unavailable |
Additional Questions for the Investment Manager
During discussions with the manager, investors should ask:
- How dependent is the strategy on the founder or CIO?
- Who takes investment decisions if the lead manager becomes unavailable?
- Has the fund experienced senior management departures previously?
- Does the investment team have a documented succession plan?
- Can the manager continue deploying capital after a key person event?
- What happens if investors reject the proposed replacement?
These questions help investors understand the difference between a contractual safeguard and the manager's actual ability to maintain investment continuity.
A strong key person clause in AIF document is useful, but it cannot completely eliminate management risk.
The quality of the investment team, internal processes and governance structure remains equally important.
Evaluate AIF and PMS Governance with ALTPORT
An investment manager's track record matters, but the people responsible for generating that track record matter just as much.
Before investing in an AIF or PMS, investors should examine management continuity, succession planning, governance standards and contractual safeguards.
At ALTPORT, our investment evaluation framework focuses on three important dimensions:
- Investment Manager Style: Understanding the manager's investment philosophy, decision-making process and experience.
- Investment Portfolio Quality: Examining portfolio construction, underlying investments and associated risks.
- Investment Performance Consistency: Evaluating historical performance across different market conditions.
These three dimensions form the foundation of our 3Is investment evaluation framework.
Explore AIF and PMS opportunities with ALTPORT and take a more informed approach to alternative investments.
Connect with ALTPORT to understand fund structures, manager capabilities and important investment documentation before making an investment decision.
Disclaimer
This article is intended for educational and informational purposes only. It does not constitute investment, legal, tax or financial advice.
AIF and PMS investments involve market risks, liquidity risks and manager-related risks. Contractual rights and investor protections depend on the applicable fund documents, agreements and regulatory provisions.
ALTPORT is an APMI-registered investment distributor and does not act as an investment adviser or portfolio manager. Investment returns are not guaranteed.