About Company
Bonanza Portfolio Limited
Bonanza is one of the fastest-growing companies in the financial services space in India with a trust of more than 2.5 decades. Since its inception in 1994, Bonanza has been helping millions of investors to navigate their investing journey with ease. Bonanza offers a one-stop solution for all investing needs ranging from equity, mutual funds, and insurance and depository services. With over 1700 outlets and service in over 600 cities across India and the UAE, Bonanza has a widespread presence which is increasing every year.For investors looking for reliable options like the Bonanza portfolio in Mumbai, this presence ensures personalized access and a deep understanding of local market requirements.
What Is Bonanza Prudentia?
Bonanza Prudentia is a Mutual Fund Portfolio Management Service (MFPMS) strategy designed around capital preservation and lower portfolio volatility.
The strategy follows a debt-focused allocation, with approximately 80% of the portfolio allocated to debt mutual funds and 20% to equity funds. The objective is to combine the relative stability of debt-oriented mutual funds with limited equity exposure for potential long-term growth.
Bonanza describes Prudentia as its highly conservative MFPMS strategy. The portfolio uses mutual funds rather than being a conventional direct-equity PMS, and the strategy is designed for investors seeking professionally managed asset allocation with a relatively defensive portfolio structure.
The minimum investment is ₹50 lakh.
Investors looking to understand the broader PMS structure can explore portfolio management services.
Bonanza Prudentia Snapshot
| Parameter | Bonanza Prudentia |
| PMS Provider | Bonanza Portfolio Limited |
| Strategy | Bonanza Prudentia |
| Product Type | Mutual Fund PMS |
| Broad Mandate | Capital preservation / lower volatility |
| Approx. Debt Mutual Fund Allocation | 80% |
| Approx. Equity Fund Allocation | 20% |
| Minimum Investment | ₹50,00,000 |
| Fund Manager | Achin Goel |
| Portfolio Structure | Mutual funds |
| Benchmark | Nifty 50 Hybrid 50:50 Index |
| Fixed Management Fee | 1% p.a. |
| Fee Frequency | Quarterly |
The strategy allocation and fee information above follows Bonanza's published Prudentia description. The current available material specifies an 80% debt / 20% equity allocation, a ₹50 lakh minimum and a 1% annual management fee charged quarterly.
Where a current AUM, inception date, exit-load figure or turnover figure could not be independently confirmed, it has deliberately been marked as not independently confirmed rather than being inferred from another Bonanza strategy.
Bonanza Prudentia Investment Strategy
Bonanza Prudentia follows a debt-first asset-allocation approach.
The strategy's central objective is to reduce the portfolio's dependence on equity-market movements by allocating the majority of the portfolio to debt mutual funds while maintaining a controlled equity allocation.
80% Debt Mutual Funds
Approximately 80% of the portfolio is allocated to debt mutual funds.
This allocation forms the defensive core of Prudentia and is intended to provide greater stability than a portfolio dominated by equities.
The debt allocation does not mean that the portfolio is free from risk. Debt mutual funds can still be affected by interest rates, credit quality, duration and changes in market liquidity.
20% Equity Funds
Approximately 20% of the portfolio is allocated to equity funds.
The equity component provides exposure to equity-market growth while keeping the overall equity allocation substantially below that of a conventional equity-focused portfolio.
This creates a portfolio structure in which equity is an important component, but not the dominant source of portfolio exposure.
Mutual Fund-Based Portfolio
Prudentia is structured around mutual funds rather than being a conventional direct-stock PMS.
The strategy uses professionally selected mutual funds and portfolio-level asset allocation to construct the investor's portfolio. Bonanza states that the strategy uses direct mutual fund plans, avoiding distributor commissions within the underlying fund selection.
Asset Allocation as the Core Decision
The most important investment decision in Prudentia is not individual stock selection. It is the allocation between defensive debt exposure and growth-oriented equity exposure.
The 80/20 framework creates a clearly defined risk posture, but actual portfolio outcomes can still vary depending on the funds selected, market conditions and changes in the underlying securities.
Rebalancing and Portfolio Management
Portfolio management involves monitoring the underlying mutual funds and the overall asset allocation.
However, a fixed mechanical rebalancing frequency should not be assumed unless specified in the latest strategy documentation. The available material does not establish a guaranteed monthly, quarterly or annual rebalancing schedule.
Bonanza Prudentia vs Prima, Optima and Platinum Alpha
Bonanza's MFPMS strategies have different portfolio objectives and asset-allocation structures.
| Strategy | Broad Mandate | Portfolio Approach | Risk Orientation |
| Bonanza Prudentia | Capital preservation and lower volatility | Primarily debt mutual funds with limited equity exposure | Conservative |
| Bonanza Prima – Conservative | Diversified growth with controlled exposure | Up to 20% direct equity, up to 70% equity-oriented funds, up to 50% debt-oriented funds and up to 50% other mutual funds | Conservative |
| Bonanza Prima – Moderate | Balanced growth and diversification | Up to 30% direct equity, up to 90% equity-oriented funds, up to 30% debt-oriented funds and up to 30% other mutual funds | Moderate |
| Bonanza Prima – Aggressive | Higher growth potential | Up to 50% direct equity, up to 100% equity-oriented funds, up to 20% debt-oriented funds and up to 30% other mutual funds | Aggressive |
| Bonanza Optima | Mutual-fund-focused portfolio construction | Up to 100% mutual funds with cash/cash-equivalent flexibility | More growth-oriented |
| Bonanza Platinum Alpha Fund | Alpha generation | Thematic and non-thematic mutual funds, precious-metal funds, direct stocks and other listed securities | Growth / alpha-oriented |
Bonanza Prima Fund – Conservative is the closest comparison for an investor evaluating a lower-volatility MFPMS option.
Bonanza Prima Fund – Moderate has a higher-growth orientation than Prudentia because its permitted equity exposure is broader.
Bonanza Optima is primarily a mutual-fund strategy and has a substantially different portfolio-construction approach.
Bonanza Platinum Alpha Fund has a much broader and more aggressive mandate focused on generating alpha across thematic and non-thematic mutual funds, precious-metal funds, direct stocks and other securities.
Bonanza Prudentia vs Prima Conservative
The most relevant comparison is between Prudentia and Prima Conservative because both are designed for investors who do not want a portfolio dominated by equity risk.
The important distinction is their allocation framework.
Prudentia has a predefined debt-first structure of approximately 80% debt mutual funds and 20% equity funds.
Prima Conservative permits a wider range of exposures, including up to 20% direct equity, 70% equity-oriented mutual funds, 50% debt-oriented mutual funds and 50% other mutual funds.
This means Prima Conservative has substantially more flexibility in how growth assets can be used, whereas Prudentia is explicitly positioned around a much more defensive 80/20 debt-equity framework.
Neither should be described as "safe" or capital guaranteed. Both remain market-linked investment solutions, and their risk depends on the underlying securities, funds and portfolio construction.
Bonanza Prudentia Minimum Investment, Fees and Exit Load
The minimum investment for Bonanza Prudentia is ₹50 lakh.
Bonanza's published Prudentia material specifies a 1% per annum fixed management fee, charged quarterly on the portfolio value.
The underlying mutual funds can also have their own expense ratios. Consequently, investors should distinguish between the PMS management fee and the expenses embedded within the underlying mutual funds.
An exit-load figure for Prudentia has not been independently confirmed from the available material and therefore should not be assumed to be the same as the 1% first-year exit load used by some other Bonanza strategies.
Investors should confirm the latest applicable fee schedule and exit terms before investing.
Key Risks of a Capital Preservation Mutual Fund PMS
Capital preservation is an objective, not a guarantee
The most important point about Prudentia is that capital preservation does not mean capital protection.
The strategy is designed to reduce volatility through its debt-heavy allocation, but the portfolio remains market-linked. There is no guarantee that the invested capital will never decline.
Interest-rate risk
The large debt allocation means interest-rate movements can affect the underlying debt mutual funds.
When interest rates change, the prices of underlying fixed-income securities can also change, depending on their duration and other characteristics.
Credit risk
Debt mutual funds are not completely free from credit risk. The financial health and credit quality of securities held by the underlying funds can influence portfolio outcomes.
Equity-market risk
Approximately 20% of Prudentia is allocated to equity funds. This portion remains exposed to equity-market movements.
Consequently, Prudentia can still experience losses when equity markets decline.
Underlying fund risk
Prudentia invests through mutual funds, which means the investor is exposed not only to the overall asset allocation but also to the investment decisions and portfolios of the underlying funds.
Fee layering
There can be a PMS management fee as well as expenses within the underlying mutual funds.
Investors should therefore evaluate the total cost of the structure rather than looking only at the PMS management fee.
Asset-allocation risk
The portfolio's risk profile depends heavily on the allocation between debt and equity. Poor allocation decisions or inappropriate changes in exposure could affect portfolio outcomes.
Liquidity risk
Although mutual funds generally offer liquidity mechanisms, the underlying securities may face liquidity constraints under stressed market conditions. The liquidity profile can therefore vary depending on the underlying funds and securities.
Inflation risk
A highly defensive portfolio may also face the risk that returns do not keep pace with inflation over long periods.
Key-person and manager risk
Portfolio construction and fund selection depend on professional investment management. Changes in the investment team or investment process can affect implementation.
Who May Consider Bonanza Prudentia?
Bonanza Prudentia may be relevant for investors who:
- Meet the ₹50 lakh minimum investment requirement
- Prioritise capital preservation as an investment objective
- Prefer lower equity exposure than a conventional equity portfolio
- Have a relatively low tolerance for equity-market volatility
- Are approaching a major financial goal
- Want professional management of a mutual-fund portfolio
- Prefer a clearly defined debt-heavy allocation
- Understand that capital preservation does not mean guaranteed capital protection
The strategy may be relevant to investors approaching retirement or those who want to reduce the volatility of a broader investment portfolio. However, suitability depends on individual circumstances, liquidity requirements, time horizon and risk tolerance.
It should not be described as a guaranteed-return or capital-protected product.
Listen to expert conversations and investment insights anytime on Spotify.
Learn about the experienced fund managers responsible for investment decisions, portfolio strategy, and long-term fund performance.
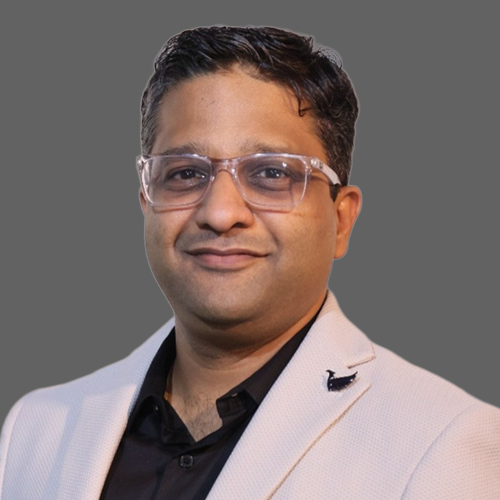
Mr. Achin Goel
Achin Goel is a seasoned financial expert currently serving as a Fund Manager and Vice President at Bonanza Portfolio Limited, where he manages high-net-worth portfolios. With over 14 years of experience, he transitioned from a background in chemical technology to become a distinguished CFA and CFP professional. Goel is renowned for his data-driven investment philosophy, often blending algorithmic insights with fundamental research to navigate volatile markets. A frequent contributor to financial media, he emphasizes disciplined asset allocation and a "checklist" approach to investing. His current strategies focus on domestic growth stories, particularly in the financial, defense, and consumer sectors, aiming for long-term alpha generation.
View Profile →Our Investment Experts
Our experts will understand your goals, map the right strategy across AIFs, PMS, Mutual Funds and Wealth Solutions, and guide you through every step.
Find answers to common questions about fund investments, performance, portfolio strategy, and investor services.
No. Capital preservation is the investment objective, but Prudentia does not provide a guarantee that the invested capital will never decline. The portfolio has approximately 80% exposure to debt mutual funds and 20% to equity funds, which is designed to reduce volatility but does not eliminate market risk.
Prudentia has a predominantly debt-oriented allocation, with approximately 80% in debt mutual funds and 20% in equity funds. Because equity exposure is limited relative to more growth-oriented strategies, the portfolio is designed to have lower sensitivity to equity-market movements. However, lower expected volatility does not mean zero volatility.
Prudentia follows a more explicitly defensive allocation, with approximately 80% debt mutual funds and 20% equity funds. Prima Conservative has a broader permitted allocation framework, including up to 20% direct equity, 70% equity-oriented mutual funds, 50% debt-oriented mutual funds and 50% other mutual funds. Therefore, Prudentia is more specifically positioned around capital preservation and debt-focused stability, while Prima Conservative provides greater flexibility across growth and defensive assets.
Within Bonanza's MFPMS range, Prudentia is positioned as the most conservative strategy. Its defining characteristic is the approximately 80% allocation to debt mutual funds and 20% allocation to equity funds.
Yes. Prudentia can decline in value. The equity portion can fall when equity markets decline, while the debt portion can also experience changes in value due to interest rates, credit events, duration and other fixed-income risks. The strategy is designed to manage volatility, not eliminate losses.
Approximately 80% of the portfolio is allocated to debt mutual funds. The remaining approximately 20% is allocated to equity funds. These are strategic allocation figures and should not be interpreted as a guarantee that the actual portfolio will remain at exactly those percentages at every point in time.
It may be considered by investors approaching retirement who prioritise lower volatility and capital preservation over aggressive equity growth. However, retirement suitability depends on factors such as the investor's income requirements, existing assets, liquidity needs, time horizon and ability to tolerate losses. It should not be treated as a capital-guaranteed retirement product.
A specific fixed rebalancing frequency has not been established in the available material. Investors should not assume that the portfolio is automatically rebalanced monthly, quarterly or annually unless the latest strategy documentation specifies such a schedule.
A current AUM figure could not be independently confirmed from the available material used for this page. Rather than inserting an AUM figure from an unrelated Bonanza strategy, it is preferable to identify the figure as unavailable until the latest applicable disclosure confirms it.
The minimum investment is ₹50 lakh.
Achin Goel is the Fund Manager associated with Bonanza Prudentia and the broader Bonanza PMS platform.
Bonanza's published Prudentia information specifies a 1% per annum fixed management fee, charged quarterly on portfolio value. The available material does not independently confirm a specific exit-load figure for Prudentia. Investors should verify the latest applicable exit-load terms before investing. The underlying mutual funds may also have their own expenses, which should be considered separately from the PMS management fee.
Subscribe to the ALTPORT newsletter
Join HNIs, family offices and NRI investors reading with us.
You're on the list
Thanks — we've added your email to the ALTPORT newsletter.