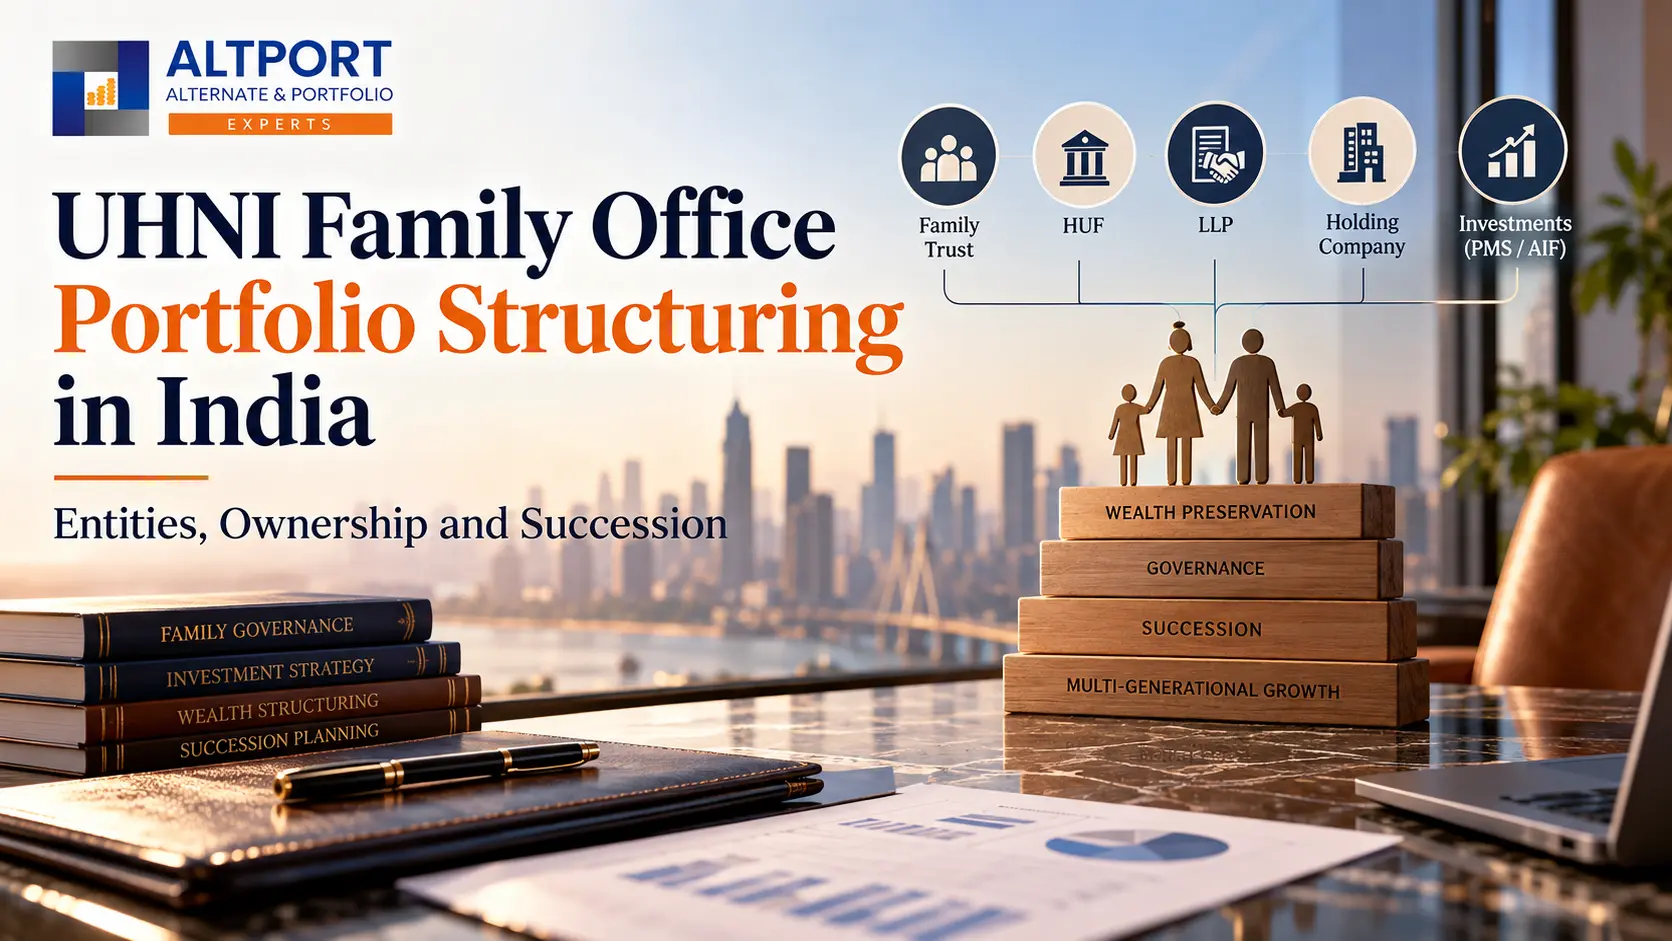
For a business-owning family, wealth management is rarely just about selecting investments. Once wealth spans operating businesses, promoter shares, listed securities, AIFs, PMS, real estate, trusts, HUF assets and multiple generations, ownership itself becomes an important financial decision.
That is where UHNI family office portfolio structuring becomes relevant.
The objective is not simply to create another entity or move investments away from an individual's name. A well-designed structure should make it easier to answer practical questions: Who owns the asset? Who controls it? Who receives the economic benefit? What happens if the founder dies? What happens when the business is sold? Which assets should remain personal, and which should sit inside a family structure?
For Indian families, family office structure India decisions also need to account for the Income-tax Act, Companies Act, FEMA, SEBI regulations, trust law, succession documents and the specific onboarding requirements of investment managers.
This article explains the framework without suggesting that one structure is universally suitable.
Important: This article is for educational purposes only and is not legal, tax, investment or estate-planning advice. Rules relating to taxation, trusts, FEMA, AIFs, PMS and GIFT IFSC can change. Any proposed structure should be reviewed by appropriately qualified legal, tax and financial professionals before implementation.
What Portfolio Structuring Means for a UHNI Family
UHNI family office portfolio structuring is essentially the process of deciding who should own which assets, through which legal vehicle, with what governance and succession arrangements.
It sits above individual investment selection.
For example, a family may have:
- Shares in the operating business
- Listed equity
- PMS accounts
- AIF commitments
- Mutual funds
- Private equity
- Real estate
- Gold and other physical assets
- Overseas investments
- Cash and fixed-income assets
- Loans, guarantees and pledged securities
All these assets do not necessarily need the same ownership structure.
The purpose of UHNI family office portfolio structuring is therefore to create clarity around ownership, control, succession, governance and risk segregation.
A useful way to think about it is:
Family wealth → Ownership → Entity → Governance → Investment → Succession
This is different from simply asking which fund or PMS strategy to choose.
In practice, UHNI wealth structuring may involve multiple entities rather than a single "family office company."
Structuring vs Asset Allocation: Two Different Decisions
One of the most common misunderstandings is treating structuring and asset allocation as the same exercise.
They are not.
Asset allocation asks:
- How much should be in equities?
- How much in fixed income?
- What portion should be allocated to alternatives?
- How much liquidity should the family maintain?
- What is the desired geographical exposure?
Structuring asks:
- Who should own the investments?
- Should they be held personally or through another entity?
- Should family members own assets separately?
- Should a trust own certain assets?
- Should a company or LLP be used for a particular purpose?
- How will ownership pass to the next generation?
Therefore, UHNI family office portfolio structuring should ideally happen alongside, but not be confused with, investment planning.
Mapping the Family Balance Sheet Before You Structure
Before discussing a family office structure India solution, start with a family balance sheet.
A simple family balance sheet can be divided into four buckets.
Operating business and promoter holdings
For many Indian business families, the operating company is the largest asset.
Map:
- Promoter shares
- Holding companies
- Subsidiaries
- Partnership interests
- ESOPs
- Unlisted investments
- Shareholder loans
- Personal guarantees
- Pledged shares
This becomes particularly important when considering a promoter holding structure.
The family's business ownership and its investment portfolio may have very different objectives and risk profiles.
Financial assets across family members
Prepare a consolidated view of:
- Listed equity
- Mutual funds
- PMS
- AIFs
- Bonds
- Fixed deposits
- Structured products
- Private equity
- Venture investments
- Cash
This exercise often reveals that the family owns the same exposure across multiple family members.
A good family office structuring process should therefore begin with consolidation rather than immediately creating another entity.
Real estate and physical assets
Map:
- Residential property
- Commercial property
- Land
- Farmhouses
- Gold
- Jewellery
- Art and collectibles
The legal ownership, usage rights, financing and succession treatment can differ significantly across these assets.
Liabilities, guarantees and pledged shares
A family balance sheet is incomplete without liabilities.
Include:
- Business loans
- Personal loans
- Guarantees
- Pledged promoter shares
- Property mortgages
- Contingent liabilities
This is especially important for how to ring-fence family wealth from business risk.
Ring-fencing does not mean that an entity automatically eliminates every legal or financial risk. The effectiveness of any separation depends on the actual ownership, documentation, guarantees, conduct and applicable law.
Who Owns What: Individual, HUF, Trust, LLP or Company
There is no universal answer to how should a family hold its investments in India.
The answer depends on the purpose of the asset, family relationships, tax considerations, succession objectives, governance requirements and regulatory eligibility.
This is why UHNI family office portfolio structuring should be approached asset-by-asset rather than entity-first.
Holding investments in personal names
Personal ownership is often the simplest structure.
It can be appropriate where:
- The asset is clearly attributable to one family member.
- Liquidity and simplicity are priorities.
- There is no immediate need for pooled ownership.
- Succession arrangements are already clear.
However, personal ownership can become complicated when substantial wealth is spread across several generations.
The key question is not simply "Is personal ownership easy?" but whether it remains appropriate as wealth and family complexity increase.
Hindu Undivided Family (HUF)
An HUF is a separate taxable person under Indian income-tax law, with its own return-filing framework.
HUFs can have investment assets, subject to the nature and source of the property and applicable law.
Therefore, HUF investment structure should be examined based on the actual family circumstances rather than treated as a generic tax-saving solution.
For can an HUF invest in PMS, the practical answer depends on the PMS provider's onboarding and KYC requirements and whether the proposed arrangement is legally permissible.
Similarly, can an HUF invest in AIF is not simply a matter of choosing "yes" or "no"; the HUF's legal and tax status, documentation and the AIF's investor eligibility and onboarding framework need to be considered.
Private trust
A private trust can be considered where the family has long-term succession or beneficiary-specific objectives.
A family office trust structure may help define:
- Beneficiaries
- Trustees
- Distribution principles
- Control mechanisms
- Succession arrangements
- Conditions around certain assets
But trust drafting matters enormously.
A private trust is not automatically tax-efficient, risk-free or suitable for every investment.
Under Indian income-tax administration, private trusts that are not eligible for ITR-7 may fall within the ITR-5 framework; tax treatment can vary depending on whether the trust is determinate or discretionary and on the applicable provisions.
LLP
An LLP for family investments can be considered when family members want a contractual governance framework with defined participation.
An LLP is a distinct legal entity from its partners, and the Income Tax Department currently states that LLPs are taxed as partnership firms, with the applicable provisions and rates subject to the law for the relevant assessment year.
That does not automatically make an LLP preferable to a trust.
The right comparison is usually LLP vs trust for family investments, based on purpose, governance, succession, taxation, contribution and distribution mechanics.
Private limited or holding company
A private company can be relevant when the family needs formal share ownership, corporate governance and defined shareholder rights.
This may be particularly relevant for:
- Promoter holdings
- Family investment companies
- Operating subsidiaries
- Joint family ventures
- Consolidated investment ownership
However, a company also introduces corporate compliance, accounting, governance and tax considerations.
That is why trust vs company for holding investments should be evaluated based on the intended function rather than the label of the entity.
How Entity Choice Changes Minimums, Taxation and Repatriation
The entity chosen in UHNI family office portfolio structuring does not automatically change every investment rule.
Different rules apply to the investor, the investment product and the transaction.
Does the entity affect the AIF or PMS minimum?
SEBI's AIF framework has historically provided a ₹1 crore minimum investment for a typical AIF investor, subject to specified exceptions including the accredited-investor framework. Current SEBI regulations and applicable circulars should be checked for the specific fund and investor category.
For PMS, SEBI's regulatory framework has prescribed a ₹50 lakh minimum investment for a client of a portfolio manager, subject to the applicable regulations and exceptions.
Therefore, family office entity structure should not be designed simply to assume that changing the ownership vehicle will reduce an investment minimum.
Always check the current product documents and onboarding rules.
How each entity is taxed on investment income
Tax treatment can differ materially between:
- Individuals
- HUFs
- Companies
- LLPs
- Determinate trusts
- Discretionary trusts
- Other taxable persons
For example, the Income Tax Department identifies LLPs separately for return filing and taxation, while HUFs have their own return framework.
A UHNI wealth structuring exercise should therefore model the after-tax outcome rather than comparing headline tax rates in isolation.
KYC, beneficial ownership and documentation
Every additional entity can introduce additional documentation.
Depending on the structure, this may include:
- PAN
- Constitutional documents
- Trust deed
- Partnership/LLP agreement
- Board resolutions
- Beneficial ownership information
- Source-of-funds documentation
- Tax residency information
- FATCA/CRS declarations
- Investment mandates
For a complex family office ownership structure, documentation should be consistent across the family balance sheet.
What changes for a non-resident beneficiary
A non-resident beneficiary or family member can introduce FEMA, tax residency and reporting considerations.
This is particularly important where assets are being transferred, distributed or invested across borders.
The structure should therefore be reviewed before the family changes residence or introduces an NRI/OCI family member into ownership.
Pooling or Separate Portfolios Across Family Members?
One of the practical decisions in UHNI family office portfolio structuring is whether to pool investments or maintain separate portfolios.
Separate portfolios may provide:
- Individual liquidity
- Clear ownership
- Personal investment mandates
- Easier attribution of gains
- Greater individual control
Pooled structures may provide:
- Centralised governance
- Consolidated reporting
- Common investment policies
- Better visibility across family wealth
- More consistent decision-making
Neither approach is automatically correct.
A family may use a hybrid model: certain long-term family assets are pooled, while personal liquidity and lifestyle assets remain individually owned.
This is an important component of how to structure family wealth in India.
Structuring Across Generations
A strong multi-generational wealth structuring framework should address not only today's ownership but also what happens when the next generation becomes involved.
Bringing the next generation onto the cap table
Families need to decide:
- Who owns shares?
- Who votes?
- Who receives dividends?
- Who participates in investment decisions?
- Who can sell?
- What happens during a family dispute?
This is where a documented family office governance structure becomes useful.
Ring-fencing wealth for minors
Minor beneficiaries require careful legal and tax planning.
Rather than simply transferring substantial assets to a minor, families may consider whether a trust or another legally appropriate arrangement can better address control, protection and succession objectives.
When to split and when to keep pooled
A family may keep certain assets pooled when the objective is collective wealth creation.
It may separate assets where:
- Family members have different liquidity needs.
- Risk profiles differ.
- Different branches of the family have independent objectives.
- There are different residency or tax considerations.
The answer should emerge from the family's governance philosophy rather than from a predetermined structure.
Structuring Around the Operating Business and Promoter Holding
For business families, the most important question may be how the investment portfolio interacts with the operating business.
A family office structure for business owners may distinguish:
Operating wealth
→ Business shares
→ Business-related assets
→ Strategic investments
from
Family wealth
→ PMS
→ AIFs
→ Listed investments
→ Bonds
→ Real estate
→ Other financial assets
This separation can make reporting and risk analysis clearer.
It also becomes relevant to how do promoter families structure non-business wealth.
A family should carefully review personal guarantees, pledges, cross-collateralisation and related-party arrangements before assuming that a separate entity completely ring-fences family wealth.
Onshore, GIFT City and Overseas: Choosing the Jurisdiction Layer
Jurisdiction is another part of UHNI family office portfolio structuring.
Domestic structures
Indian families may use Indian individuals, HUFs, trusts, LLPs or companies depending on the intended purpose and legal/tax framework.
The simplest structure that meets the family's objectives is often worth considering before introducing additional entities.
GIFT City and IFSC structures
GIFT IFSC has developed a dedicated framework for family investment structures.
Under the current IFSCA Fund Management Regulations, a Family Investment Fund may be established in the IFSC as a company, a contributory trust, an LLP or another form permitted by IFSCA, subject to the prescribed conditions.
In April 2026, IFSCA announced registration of its first foreign Family Investment Fund under the 2025 Fund Management Regulations, describing the framework as a platform for family wealth management and investments into India and global markets.
This makes GIFT IFSC an important jurisdiction to evaluate for some internationally oriented families, but not a default answer for every Indian family.
Overseas holdings under LRS and FEMA
A crucial point for UHNI wealth structuring is that the Liberalised Remittance Scheme is a facility for resident individuals, not a general route for corporates, partnership firms, HUFs or trusts. RBI's framework states that LRS is available to resident individuals and is not available to those entities.
Therefore, a family should not assume that an entity can simply use an individual's LRS allowance.
Overseas ownership may instead involve the applicable FEMA Overseas Investment framework, depending on the investor and transaction.
Succession, Nomination and Transmission of AIF and PMS Holdings
Succession is where family office succession planning moves from theory to implementation.
A portfolio can be well invested and still poorly structured if the family has not documented what happens after the death of an owner.
Nomination versus a will
Nomination and succession are not interchangeable concepts.
A nomination can facilitate transmission according to the applicable rules and product documentation, while a will sets out testamentary intentions.
Families should coordinate:
- Will
- Nomination
- Trust deed
- Shareholder agreements
- Investment account records
- Beneficiary details
This becomes especially important when asking nomination vs will for investments.
How AIF units transmit
The answer to how to transfer AIF units to legal heirs depends on the AIF documents, applicable succession law, investor constitution and the fund's transfer/transmission process.
The practical question is therefore not merely "Can it be transferred?"
It is:
- Who becomes legally entitled?
- What documents establish that entitlement?
- Does the fund permit transfer or transmission?
- What KYC and tax documentation is required?
- Are there restrictions in the PPM or contribution agreement?
This is also why transmission of AIF units on death should be planned before an event occurs.
How PMS holdings transmit
For what happens to PMS holdings after death, the exact process depends on the portfolio management agreement, account structure, nomination, applicable succession law and the custodian/broker's procedures.
The family should maintain a consolidated transmission file containing:
- Investment account details
- Nominee information
- PAN
- Demat details
- PMS agreement
- AIF documents
- Trust documents
- Will
- Key contact information
Governance: Who Signs Off on What
A mature family office governance structure should answer four questions:
Who decides?
Who executes?
Who monitors?
Who can override?
For example:
| Decision | Possible responsibility |
| Strategic asset allocation | Family investment committee |
| Individual investment selection | Investment team/adviser |
| Trust distributions | Trustees |
| Business decisions | Board/promoters |
| Personal liquidity | Individual family member |
| Succession | Family + legal advisers |
| Tax structuring | Tax adviser |
| Legal documentation | Legal counsel |
The actual framework will vary.
The purpose is to prevent a situation where investment authority, legal ownership and economic ownership become confused.
What Changes When the Family Sells the Business
A business sale can fundamentally change UHNI family office portfolio structuring.
Before a sale, most family wealth may be concentrated in one operating company.
After the sale, the family may suddenly hold:
- Cash
- Listed securities
- Bonds
- AIFs
- PMS
- Private equity
- Real estate
- Overseas assets
This is the point at which structuring wealth after selling a business becomes particularly relevant.
The family should consider:
- Liquidity requirements
- Capital preservation
- Tax liabilities
- Succession
- New investment governance
- Concentration risk
- Family member roles
- Geographic diversification
- Philanthropic objectives
- Future business investments
A business exit is therefore not merely an investment event. It can be an ownership and governance reset.
Common Structuring Mistakes Indian Families Make
Several recurring mistakes can undermine otherwise sophisticated UHNI family office portfolio structuring.
1. Creating entities before defining the objective
A trust, LLP or company is a tool. It is not the objective.
2. Optimising only for tax
Tax is one input.
Succession, control, compliance, liquidity and governance also matter.
3. Ignoring the family balance sheet
A new investment structure should be viewed alongside existing promoter holdings, guarantees and liabilities.
4. Mixing business and family wealth
Without clear separation, the family's investment portfolio can become entangled with operating-business risk.
5. Treating nomination as a complete succession plan
Nomination should be coordinated with the broader succession documentation.
6. Assuming all AIFs and PMS providers accept every entity
Investor eligibility and onboarding can differ.
7. Creating too many entities
Complexity has a cost.
Every additional entity can mean additional accounting, compliance, KYC, governance and professional fees.
8. Ignoring future generations
A structure that works for the founder may not work when three branches of the family become shareholders or beneficiaries.
9. Treating GIFT City as a universal solution
GIFT IFSC offers specific structures and regulatory possibilities, but whether they are relevant depends on the family's objectives, residency, assets and investment needs.
10. Failing to document the structure
A sophisticated family office entity structure is useful only when the underlying ownership and governance documents actually support it.
How Indian Families Approach Structuring Decisions
In practice, UHNI family office portfolio structuring can be approached through a simple sequence.
Step 1: Consolidate
Create a single family balance sheet.
Step 2: Classify
Separate business assets, investment assets, personal assets and liabilities.
Step 3: Identify objectives
Define:
- Wealth preservation
- Growth
- Income
- Succession
- Philanthropy
- Liquidity
- Global diversification
Step 4: Identify ownership
Ask who owns what today.
Step 5: Identify the intended ownership
Ask who should own each asset in five, ten and twenty years.
Step 6: Compare structures
Evaluate individual, HUF, trust, LLP and company structures based on the specific asset and objective.
Step 7: Test taxation and compliance
Model the tax and administrative implications before implementation.
Step 8: Test succession
Ask what happens if:
- The founder dies.
- A beneficiary dies.
- A beneficiary becomes an NRI.
- The family sells the business.
- A family branch exits.
- A dispute arises.
Step 9: Document governance
Define decision rights and signing authority.
Step 10: Review periodically
A UHNI family office portfolio structuring framework should evolve as the family, business and regulatory environment change.
A Practical Decision Framework
For families asking should I invest in personal name or through a trust, the answer should start with the objective rather than the tax rate.
| Question | What it helps determine |
| Who is the economic beneficiary? | Ownership |
| Who should control the asset? | Governance |
| Is the asset intended for one person or the family? | Pooling |
| Is succession a major objective? | Trust/will/ownership design |
| Is the asset connected to the business? | Risk segregation |
| Are beneficiaries minors? | Control and succession |
| Are beneficiaries non-resident? | FEMA/tax review |
| Is the investment illiquid? | Transmission planning |
| Is global exposure required? | Jurisdiction/FEMA |
| How complex can the family administration become? | Entity selection |
This is the practical heart of UHNI family office portfolio structuring.
Build the Structure Before the Wealth Gets Complicated
Your Wealth Deserves a Structure, Not Just a Portfolio
For a UHNI family, the question is no longer only "Where should we invest?"
It is also:
Who should own it?
Who should control it?
How should it pass to the next generation?
What happens if the business is sold?
How should business wealth and family wealth be separated?
At ALTPORT, the conversation around UHNI family office portfolio structuring can begin with a consolidated view of the family's assets, liabilities, investment objectives and succession priorities.
The objective is to help families evaluate the available structures—rather than assuming that one structure works for everyone.
Disclaimer: This content is for educational and informational purposes only and should not be construed as investment, legal, tax or succession-planning advice. Investment and structuring decisions involve risks and may have tax and regulatory consequences. Please consult qualified legal, tax and financial professionals before implementing any structure. Regulations are subject to change.