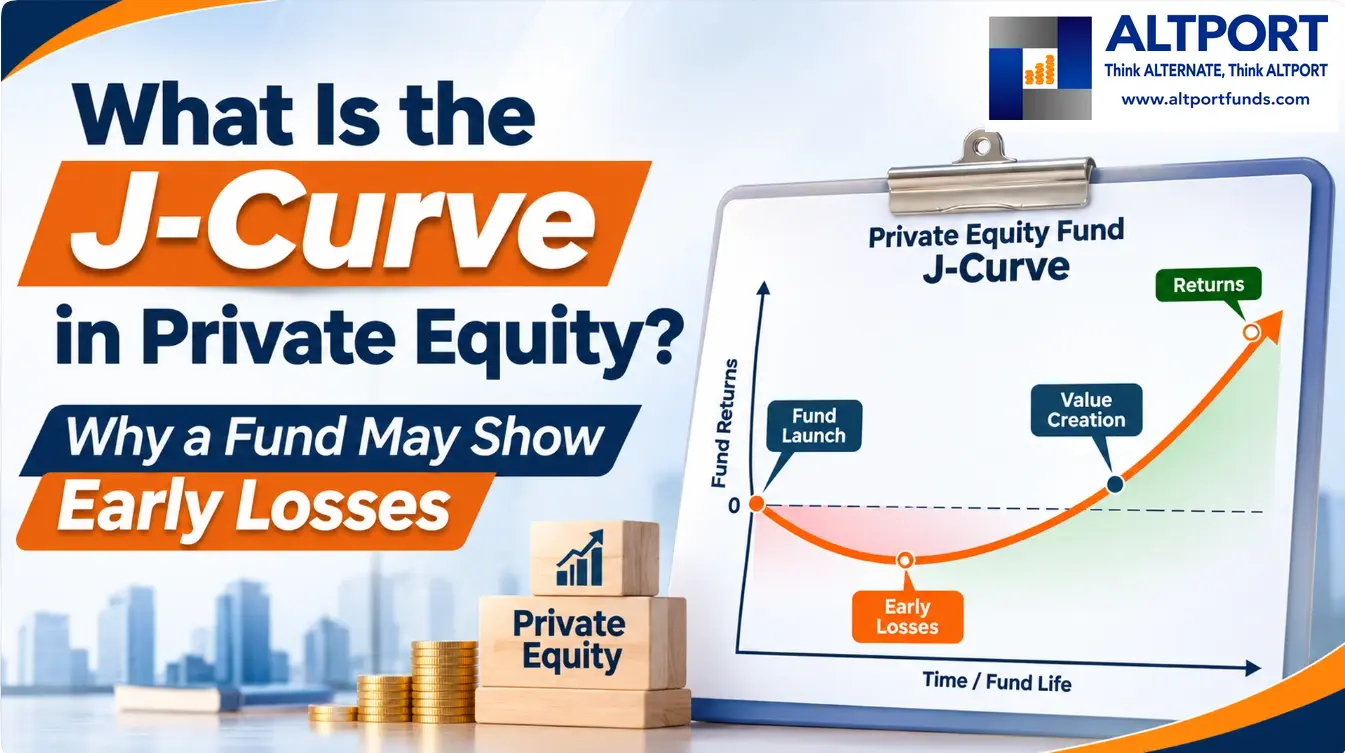
A private equity fund may report negative returns during its first few years, even when its investments are progressing as planned. This pattern is known as the J-curve in private equity.
The fund initially records expenses, management fees and investment costs. However, distributions from portfolio companies usually take longer to arrive. As investments mature and exits generate proceeds, the fund may begin recovering its initial losses.
For investors, understanding this pattern is important when evaluating private equity fund performance. Early negative returns do not automatically indicate poor investment decisions. Equally, the J-curve should not become an excuse for consistently weak results.
This guide explains how the pattern develops, how it affects AIF performance metrics and what investors should examine before judging an early-stage fund.
What Is the J-Curve in Private Equity?
The J-curve in private equity describes the pattern in which a fund's reported returns initially decline before recovering and potentially moving into positive territory.
It gets its name from the shape of the performance curve. When plotted over time, the curve moves downward during the early investment period and rises as portfolio investments mature and generate returns.
A typical private equity fund follows this sequence:
- Initial investment: The fund makes capital calls and invests in portfolio companies.
- Early expenses: Management fees, transaction costs and operating expenses reduce the fund's reported value.
- Development period: Portfolio companies work towards business expansion, operational improvements or other value-creation objectives.
- Realisation period: The fund exits investments through strategic sales, secondary transactions, buybacks or public listings.
- Distributions: Investors receive proceeds, which can improve realised returns.
The Private equity J-curve is therefore a representation of how fund performance may evolve across its lifecycle. It is not a guaranteed pattern or a standard return schedule.
The J-curve effect is particularly relevant to closed-ended funds, where capital is invested over several years and exits generally happen later. Investors exploring private equity investments through Category II AIFs should understand how investment periods, holding periods and exit timelines can affect reported performance.
Why Does a Private Equity Fund Follow a J-Curve Pattern?
The J-curve in private equity develops because investment outflows usually begin before meaningful cash inflows. Three factors commonly explain this gap.
Management Fees and Fund Expenses
Private equity funds incur expenses from the beginning of their operations. These may include management fees, legal expenses, audit costs, administration charges, transaction expenses and other fund-level costs.
Management fees are generally charged according to the terms specified in the fund documents. The calculation may be based on committed capital, invested capital or another agreed basis. The applicable basis can change during the fund's lifecycle.
This matters because investors may bear expenses before the portfolio generates cash returns.
For example, a fund with ₹500 crore in committed capital may charge an annual management fee of 2% on committed capital during its investment period. This would represent ₹10 crore annually before considering other expenses.
The actual fee structure varies across funds. Investors should examine the contribution agreement and private placement memorandum (PPM) to understand how fees affect net returns. Read our guide to the AIF private placement memorandum (PPM) to understand the fund terms and disclosures investors should review.
Capital Calls Before Distributions
A private equity fund does not necessarily invest all committed capital immediately.
Instead, it issues capital calls when funds are required for investments and expenses. Investors contribute the requested amount against their committed capital.
This creates a difference between committed capital and paid-in capital. Committed capital represents the investor's total contractual commitment, while paid-in capital is the amount actually contributed.
During the early years, capital calls may continue while fund distributions remain limited. This imbalance can pull down reported performance.
The J-curve in private equity becomes more visible when substantial capital has been deployed but portfolio companies have not yet generated exit proceeds.
Investors can learn more about AIF capital calls and drawdowns to understand how funds request committed capital and how drawdown schedules work.
Portfolio Company Development and Valuation
Private equity managers typically invest in businesses that require capital, operational improvements, expansion or restructuring.
These changes take time. A portfolio company may need several years to increase revenue, improve margins, reduce debt or strengthen its market position.
Valuations can also fluctuate during this period. Changes in market conditions, business performance, comparable company multiples and financial forecasts may lead to unrealised gains or losses.
As a result, the J-curve effect may reflect both actual fund expenses and changes in the estimated value of investments.
Investors should distinguish between realised losses and unrealised valuation movements. They represent different stages of investment performance and carry different implications.
How the J-Curve Develops Over a Fund's Life
The J-curve in private equity generally develops across three broad stages. The exact timing depends on the fund strategy, investment period, portfolio maturity and exit environment.
| Fund stage | Typical activity | Possible performance pattern |
| Investment period | Capital calls, acquisitions and initial expenses | Negative or muted returns |
| Value-creation period | Business expansion, operational changes and valuation updates | Gradual improvement, with possible fluctuations |
| Realisation period | Exits, repayments and fund distributions | Higher realised proceeds and potential positive returns |
The private equity fund lifecycle often extends across several years. Many closed-ended funds have a fund term of around 8–10 years, including extensions where permitted by their documents. This is not a universal timeline.
The J-curve in AIF structures may also vary depending on the category and investment strategy. A venture capital fund investing in early-stage companies may have a different return timeline from a buyout or growth equity fund.
Investors should assess the fund's vintage year, investment pace and exit activity rather than compare every fund against the same timeline.
J-Curve Example: How a Private Equity Fund's Returns Change Over Time
Consider a hypothetical private equity AIF with ₹100 crore in committed capital.
The fund calls capital in stages, invests in portfolio companies and incurs expenses before receiving meaningful exit proceeds.
| Year | Cumulative paid-in capital | Cumulative distributions | Illustrative NAV |
| Year 1 | ₹30 crore | ₹0 crore | ₹27 crore |
| Year 2 | ₹60 crore | ₹0 crore | ₹55 crore |
| Year 3 | ₹80 crore | ₹5 crore | ₹78 crore |
| Year 4 | ₹90 crore | ₹25 crore | ₹95 crore |
| Year 5 | ₹90 crore | ₹60 crore | ₹65 crore |
The figures are illustrative and do not represent actual fund performance.
In Year 1, the fund has called ₹30 crore but reports an NAV of ₹27 crore. Initial expenses and investment valuations account for the difference.
By Year 3, the fund has started distributing money. However, the cumulative distributions remain below the capital contributed.
In Year 4, portfolio valuations and distributions have improved. By Year 5, cumulative distributions have increased substantially.
This example shows how the J-curve in private equity can move from an initial decline towards recovery as investments mature.
However, NAV and distributions must be considered together. A higher NAV does not automatically mean investors have received cash, while distributions alone do not show the remaining value of the portfolio.
J-Curve vs IRR, DPI, RVPI and TVPI
The J-curve is a way to understand the timing of fund performance. It should be evaluated alongside other AIF performance metrics.
J-Curve vs IRR
The Internal Rate of Return (IRR) measures the annualised rate of return based on the timing and amount of cash flows.
The J-curve in private equity describes the typical movement of returns over the fund's lifecycle. IRR provides a numerical measure of performance based on cash-flow timing.
The two are related, but they are not interchangeable.
A fund may report a negative early IRR because capital has been called and expenses incurred before distributions begin. Later cash inflows can improve the IRR.
Investors should also understand whether the reported figure is gross or net IRR. Net IRR accounts for applicable fund-level fees and expenses, while gross IRR generally reflects investment-level performance before those deductions.
J-Curve vs DPI and RVPI
Distributions to Paid-in Capital (DPI) measures how much money a fund has distributed relative to the capital investors have contributed.
DPI = Cumulative Distributions ÷ Cumulative Paid-in Capital
RVPI = Residual NAV ÷ Cumulative Paid-in Capital
DPI focuses on realised cash returned to investors. RVPI reflects the value of investments that have not yet been realised.
During the early years, DPI may remain low because exits are limited. RVPI may account for most of the fund's reported value.
The J-curve in private equity helps explain why these measures can look different during the investment period.
J-Curve vs TVPI
Total Value to Paid-in Capital (TVPI) combines realised distributions and residual portfolio value.
In simple terms:
TVPI = DPI + RVPI
A TVPI below 1.0x means the fund's combined distributions and remaining NAV are below the capital paid in. A TVPI above 1.0x indicates that the combined value exceeds paid-in capital.
| Metric | What it measures | What investors learn |
| J-curve | Return movement over time | Whether early losses are followed by recovery |
| IRR | Annualised return based on cash-flow timing | How efficiently capital has generated returns over time |
| DPI | Distributions against paid-in capital | How much cash has been returned |
| RVPI | Residual NAV against paid-in capital | How much value remains unrealised |
| TVPI | Distributions plus residual NAV against paid-in capital | Total realised and unrealised value |
No single metric provides a complete picture of private equity fund returns. Investors should examine all these measures together.
Does a Negative J-Curve Mean a Fund Is Performing Poorly?
No. A negative J-curve does not automatically mean poor fund performance.
Early losses may result from normal fund expenses, investment deployment and the time required to develop portfolio companies. However, investors should examine whether the decline is consistent with the fund's investment strategy and expected timeline.
A negative J-curve deserves closer attention when:
- Portfolio companies repeatedly miss business or financial targets.
- NAV declines without a clear explanation.
- Unrealised losses continue across several reporting periods.
- Management fees and expenses remain high relative to deployed capital.
- The fund has limited exit progress despite an ageing portfolio.
- Valuations appear optimistic compared with operating performance.
The J-curve in private equity should be assessed against the fund's vintage year, investment strategy and comparable funds.
A fund should not be judged only by its early losses. It should also not receive an automatic pass because it is still young.
What Can Make a J-Curve Deeper or Shallower?
The depth and duration of the J-curve effect can differ significantly between funds.
| Factor | Potential impact |
| High management fees | May increase early expenses and deepen the decline |
| Slow capital deployment | Can delay value creation and affect early returns |
| Early profitable exits | May shorten the negative phase |
| Strong portfolio performance | Can support higher NAV and future distributions |
| Market downturns | May reduce valuations and delay exits |
| Investment strategy | Determines the time required to develop and realise investments |
| Fund size and diversification | Can influence deployment pace and portfolio-level outcomes |
The J-curve in private equity may be deeper in funds investing in early-stage businesses. These companies often need more time to establish operations, achieve profitability and attract buyers.
A buyout fund investing in established businesses may have a different profile. However, leverage, market conditions and acquisition valuations can still affect its results.
The J-curve in venture capital vs private equity is therefore not identical. Venture capital funds may experience longer periods of unrealised value and uncertain exits. Buyout funds may generate cash flows earlier, depending on their portfolio and exit strategy.
How Should AIF Investors Evaluate the J-Curve?
Investors evaluating the J-curve in private equity should look beyond the headline IRR or a single NAV update.
The following checks can provide a more complete view:
- Check the vintage year and fund age
Compare the fund with others launched in a similar period. Funds from different vintage years may face different market conditions, entry valuations and exit opportunities.
- Review capital deployment
Examine committed capital, paid-in capital and uncalled commitments. Understand how quickly the manager has deployed capital and whether the investment pace matches the stated strategy.
- Examine portfolio quality
Review the number of investments, sector exposure, company-level performance, concentration and progress against business plans.
- Separate realised and unrealised performance
Look at DPI and RVPI together. A fund with a high TVPI but low DPI may still depend heavily on unrealised valuations.
- Understand fees and expenses
Check management fees, fund expenses, transaction costs, carried interest and the distribution waterfall. Understand how management fees affect private equity returns and the amount investors ultimately receive.
- Review valuation practices
Understand how the manager values unlisted investments, how frequently valuations are updated and whether valuation changes reflect actual business developments.
- Assess exit progress
Examine completed exits, partial exits, write-offs and the manager's plans for remaining investments. A mature fund with limited realisations may need closer scrutiny.
The J-curve in private equity becomes more meaningful when supported by transparent reporting and evidence of portfolio progress.
Investors should also review the fund's IRR, DPI, RVPI, TVPI and underlying private equity cash flows. These measures help distinguish temporary early losses from persistent performance concerns.
For a broader evaluation framework, read ALTPORT's AIF and PMS manager due diligence checklist. You can also explore our guide on how to choose the right AIF in India for additional fund-selection considerations.
Explore Private Equity and AIF Opportunities with ALTPORT
Understanding early fund performance is an important part of AIF due diligence. Investors need to examine the fund manager's approach, portfolio quality, valuation practices, fee structure and consistency of performance.
ALTPORT is an APMI-registered investment platform and distributor offering access to information on alternative investment opportunities, including AIFs and PMS.
Explore fund details, compare relevant performance information and understand the structure before making an investment decision. Visit ALTPORT to learn more about alternative investment opportunities and the factors that matter during due diligence.
Disclaimer: This article is for informational and educational purposes only. It does not constitute investment, legal or tax advice or a recommendation to invest in any security or fund. Investments in AIFs and private equity carry market, liquidity, valuation and capital loss risks. Past performance does not guarantee future results. Investors should review the relevant fund documents and consult qualified professionals where required.