For an AIF investor, the headline return is only part of the story. The other part is understanding how much of that return ultimately belongs to the investor and how much goes to the fund manager as performance-linked compensation.
Carried Interest in AIF refers broadly to the manager's share of profits or additional returns under the fund's agreed fee structure. In India, the same economics may be described in fund documents as performance fee, incentive fee, additional return or carry. The exact calculation depends on the AIF's terms, including the hurdle rate, catch-up, waterfall, fees and timing of distributions.
SEBI's prescribed AIF PPM framework specifically requires disclosure of items such as hurdle rate, catch-up, carry or additional-return computation and the method of calculating carry, including whether it is calculated deal by deal or on the aggregate portfolio.
That makes Carried Interest in AIF an important due-diligence point rather than a technical footnote.
Who Receives the Carry in an AIF?
The carry generally goes to the investment manager, sponsor or an associated carried-interest vehicle, depending on how the fund is structured.
The important point is that investors should not assume that every rupee of profit belongs entirely to them after expenses. The AIF's PPM sets out the agreed AIF profit sharing mechanism and the sequence in which capital, preferred return and additional returns are distributed.
Carried Interest in AIF is therefore usually linked to successful investment performance rather than simply being a fixed charge on assets.
Carried Interest vs Management Fee: What Is the Difference?
Management fee and carry perform different economic functions.
| Fee | Broad purpose | Usually linked to |
| Management fee | Pays for operating and managing the fund | AUM, committed capital or another agreed base |
| Carried interest / performance fee | Rewards performance above agreed conditions | Fund profits or additional returns |
| Fund expenses | Covers costs incurred by the fund | Actual expenses under fund documents |
A management fee may be payable even when investment performance is weak, depending on the fund's terms. Carry is generally performance-linked.
This distinction matters because an AIF fee structure can include both. An investor looking only at the management fee may therefore underestimate the total economic cost.
SEBI's PPM framework requires AIFs to provide investors with disclosures around fees, expenses and distribution mechanics.
What Is the Typical Carried-Interest Percentage?
There is no single regulatory percentage that applies to every AIF.
Twenty percent is a widely recognised industry convention in alternative investments, but actual terms can differ by fund, strategy, vintage, investor class and negotiating arrangements. Historical SEBI material has also described 20% as a global industry practice, while current market commentary notes that Indian structures vary.
So, when a fund says it charges 20% carry, the more important question is: 20% of what?
It could mean 20% of returns above a hurdle, 20% after a catch-up, or another calculation specified in the PPM.
When Does an AIF Manager Become Entitled to Carry?
The answer depends on the distribution waterfall.
Carried Interest in AIF may become payable only after investors receive their return of capital and preferred return. In other structures, the manager may receive performance compensation earlier, particularly under deal-by-deal or American-style waterfalls.
The PPM should explain:
- Return of capital
- Hurdle or preferred return
- Catch-up, if applicable
- Carry percentage
- Distribution sequence
- High-water mark provisions, where applicable
- Clawback provisions
- Whether calculations are gross or net of specified fees and expenses
There is no substitute for reading the actual waterfall.
Why Is Investor Capital Returned Before Carry Is Paid?
The basic logic is straightforward.
If an investor contributes ₹1 crore, that original ₹1 crore is capital, not profit. A waterfall may therefore first return the investor's capital before allocating the remaining profit between investors and the manager.
This is commonly referred to as return of capital AIF treatment.
The exact sequence varies. Some structures may first return capital, then pay a preferred return, followed by catch-up and carry. Others may use different sequencing.
The principle is to establish what investors are entitled to receive before the manager participates in the residual economics.
How Is Carried Interest Calculated?
A simplified calculation is:
Carry = Applicable carry percentage × eligible profit under the waterfall
But "eligible profit" is where the real complexity starts.
It may depend on:
- Hurdle rate
- Preferred return
- Catch-up
- Management fees
- Fund expenses
- Previous distributions
- Unrealised or realised gains
- High-water mark
- Deal-by-deal or whole-fund calculation
- Taxes and other adjustments specified in the documents
Therefore, Carried Interest in AIF cannot be calculated accurately from the headline carry percentage alone.
Is Carry Calculated on Total Profit or Profit Above the Hurdle?
That depends on the fund documents.
A fund may provide carry above hurdle rate, meaning the manager participates only after investors have received the agreed hurdle or preferred return.
For example, if the hurdle is 8% and the applicable calculation produces a return below 8%, the manager may receive no carry under that structure.
Other arrangements may include catch-up provisions, which materially change the calculation after the hurdle has been crossed.
What Is a Hurdle Rate or Preferred Return?
An AIF hurdle rate is a specified return threshold that investors must generally receive before performance-linked compensation becomes payable under the agreed waterfall.
A preferred return AIF structure therefore gives investors priority up to the stated threshold, subject to the exact contractual terms.
The hurdle may be expressed as:
- A fixed annual percentage
- A benchmark-linked return
- A compounded or simple return
- A pre-tax or post-tax calculation
SEBI's PPM template specifically calls for disclosure of the hurdle calculation methodology, applicability across classes and whether it is calculated pre-tax or post-tax.
How Does a Hard Hurdle Affect Carried Interest?
Under a hard hurdle AIF structure, the manager generally earns carry only on returns above the hurdle.
Consider a simplified example:
- Investment: ₹1 crore
- Hurdle: 8%
- Final value: ₹1.20 crore
- Profit: ₹20 lakh
If the agreed hurdle is ₹8 lakh for the relevant period, the amount eligible for carry would be considered after satisfying the hurdle, subject to the fund's precise waterfall.
The important point is that crossing the hurdle does not automatically mean the entire profit becomes subject to carry.
How Does a Soft Hurdle Affect Carried Interest?
A soft hurdle AIF can operate differently.
Once the fund crosses the hurdle, the carry calculation may apply to a broader portion of the profit, potentially including the return below the hurdle, depending on the contractual structure.
That difference can have a meaningful effect on investor economics.
This is why investors should never compare two AIFs simply by saying, "Both charge 20% carry." A 20% carry with a hard hurdle can produce a different outcome from 20% carry with a soft hurdle and catch-up.
What Is a Catch-Up Clause?
A catch-up clause AIF provision determines what happens after investors have received their preferred return.
A catch-up can allow the manager to receive a larger share of subsequent distributions until the agreed carry split is reached.
A full catch-up AIF structure can allow the manager to catch up fully to the agreed carried-interest percentage after the hurdle is satisfied.
A partial catch-up AIF allows only part of that catch-up.
For investors, the difference can be significant because the catch-up affects how much profit remains with investors after the hurdle has been crossed.
How Does the Distribution Waterfall Affect Carry?
The AIF distribution waterfall is essentially the rulebook for deciding who receives cash, how much and in what order.
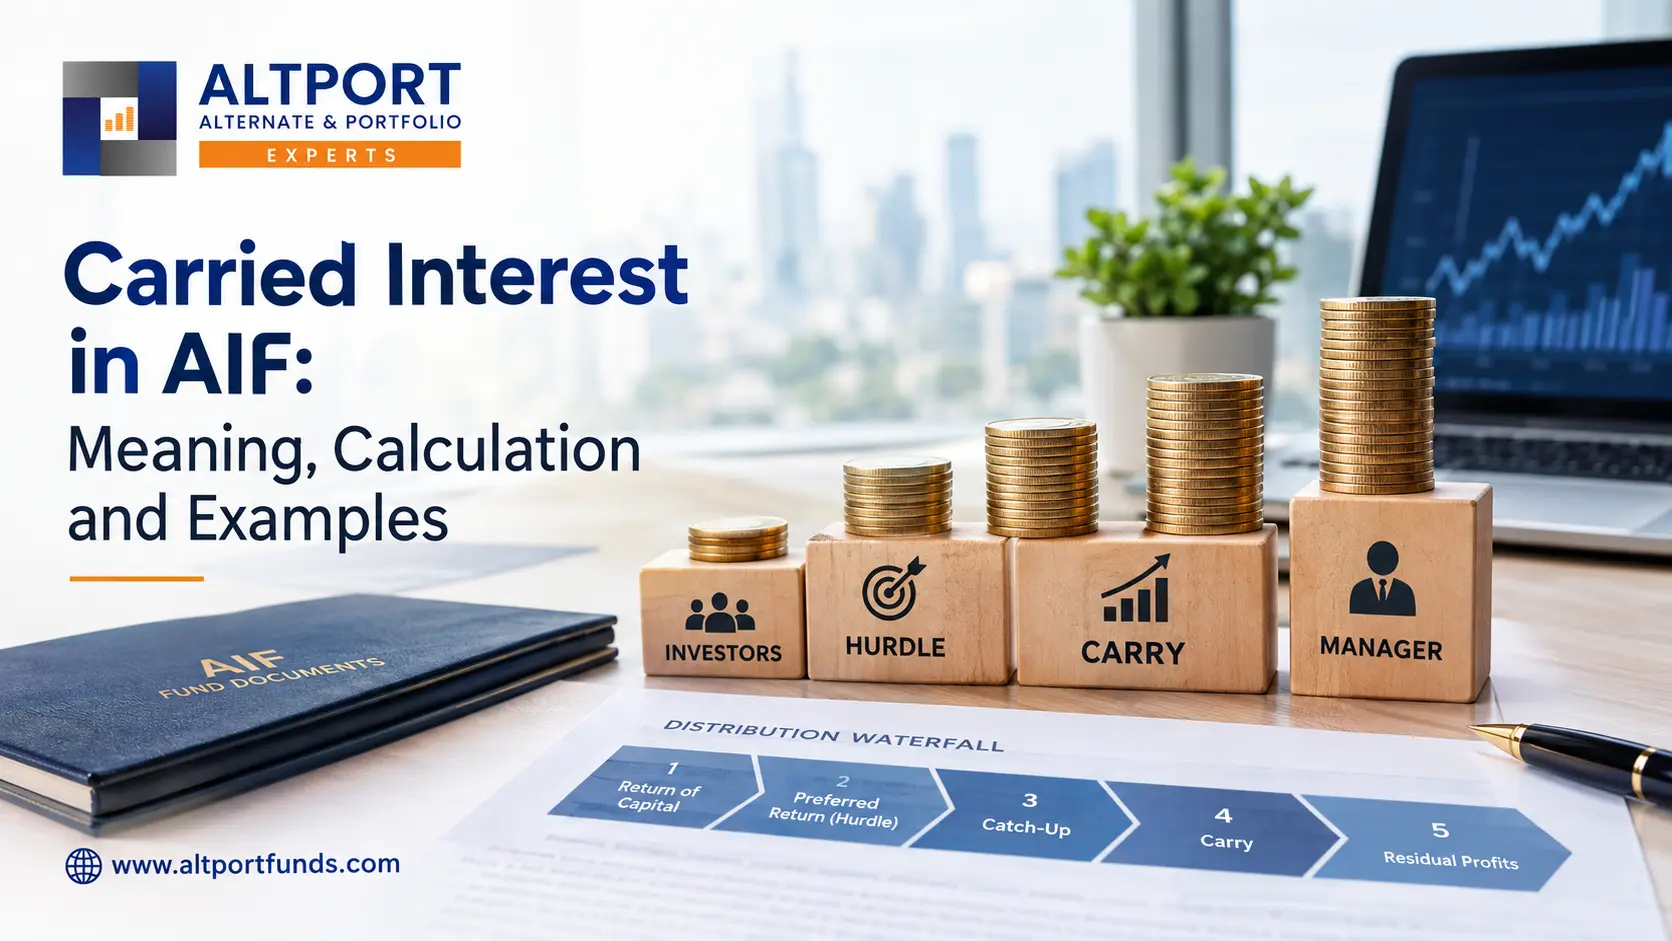
A simplified waterfall might look like:
- Return investor capital
- Pay preferred return or hurdle
- Apply catch-up, if applicable
- Split remaining profit between investors and manager
- Apply any final adjustments or clawback
SEBI's prescribed PPM framework requires disclosure of the distribution waterfall and carry calculation, including whether additional return is calculated on a deal-by-deal or aggregate portfolio basis.
That makes the waterfall one of the most important sections for an investor conducting due diligence on Carried Interest in AIF.
European Waterfall vs American Waterfall
The distinction mainly concerns when carry is calculated and paid.
European or Whole-Fund Waterfall
A European waterfall AIF generally considers the fund at the portfolio level.
It is also commonly described as a whole-fund waterfall AIF. Investors typically receive capital and the agreed preferred return before the manager participates in overall profits.
American or Deal-by-Deal Waterfall
An American waterfall AIF is commonly associated with deal-level calculations.
Under a deal-by-deal waterfall AIF, the manager may receive carry from realised profitable investments before the entire portfolio has been fully realised.
The trade-off is timing. If later investments perform poorly, a clawback may become important.
Worked Example: Carry Without a Hurdle Rate
Assume:
- Investor capital: ₹1 crore
- Final proceeds: ₹1.30 crore
- Total profit: ₹30 lakh
- Carry: 20%
- No hurdle or catch-up
Carry:
₹30 lakh × 20% = ₹6 lakh
Investor receives:
₹1 crore capital + ₹24 lakh profit = ₹1.24 crore
Manager receives ₹6 lakh as carry, before considering any other applicable fees, expenses or taxes.
This is a simplified AIF carry example, not a universal calculation method.
Worked Example: Carry with an 8% Hard Hurdle
Assume:
- Investment: ₹1 crore
- Final proceeds: ₹1.30 crore
- Profit: ₹30 lakh
- Hurdle: 8%
- Carry: 20%
- Simplified one-year calculation
- No catch-up
Preferred return:
₹1 crore × 8% = ₹8 lakh
Profit above hurdle:
₹30 lakh - ₹8 lakh = ₹22 lakh
Carry:
₹22 lakh × 20% = ₹4.4 lakh
The investor's simplified economic entitlement before other adjustments is ₹25.6 lakh of profit, plus the ₹1 crore capital.
The actual calculation can differ if the fund uses compounding, multiple cash flows, expenses, taxes or another waterfall.
Worked Example: Hurdle, Catch-Up and 20% Carry
Suppose the fund generates ₹30 lakh of profit, with:
- 8% preferred return
- 20% carry
- Full catch-up
- Simplified one-year calculation
First, investors receive ₹8 lakh as preferred return.
The catch-up then allows the manager to receive additional distributions until the agreed 20% profit-sharing economics are reached.
Only after the catch-up is completed is the remaining profit divided according to the agreed split.
This example shows why the phrase Carried Interest in AIF tells you very little without the surrounding waterfall terms. Two funds with the same hurdle and carry percentage can produce different investor outcomes because their catch-up mechanics differ.
What Is a Clawback Clause?
A clawback clause AIF provision protects investors when the manager has already received carry from early profitable exits but subsequent investments reduce overall fund performance.
For example, an early investment generates a large gain and produces carry. Later investments lose money. At the end of the fund, the manager may have received more carry than the final whole-fund economics justify.
A clawback can require the manager to return the excess amount, subject to the contractual terms.
This is particularly relevant when carry is calculated deal by deal.
When Is Carried Interest Paid to the Manager?
When is carried interest paid depends on the fund's structure.
It may be paid:
- When specified performance conditions are met
- At portfolio realisations
- At periodic distribution events
- At the end of a fund's tenure
- After a whole-fund waterfall is satisfied
Investors should check whether carry is calculated on realised gains, unrealised gains or another defined basis, and whether subsequent adjustments are possible.
How Does Carry Affect Gross and Net Investor Returns?
The difference between gross vs net AIF returns is crucial.
Gross returns generally represent portfolio performance before certain fees and expenses.
Net returns are closer to what the investor actually receives after applicable fees, expenses and performance-linked compensation.
For example, a fund can show a strong gross return while the investor's net return is lower because of management fees, carry, fund expenses and other charges.
Carried Interest in AIF therefore belongs in the same conversation as net IRR, distributions and total investor costs, not just headline portfolio performance.
How Is Carried Interest Taxed in India?
Carried interest tax India treatment can depend on the legal structure, recipient, nature of the payment and applicable tax provisions.
It is important not to assume that "carry" automatically has one fixed tax treatment.
Category I and Category II AIFs have specific pass-through provisions for eligible income under the Income-tax framework, while Category III AIF taxation works differently. The tax treatment of the manager's own carry or performance-linked income must be considered separately from taxation of an investor's AIF income.
Tax rules can also change. Investors and managers should therefore obtain tax advice based on the specific fund documents and their circumstances rather than relying on a generic carry calculation.
Where Is the Carried-Interest Structure Disclosed?
The primary document to examine is the AIF's Private Placement Memorandum (PPM) and related fund documents.
SEBI describes the PPM as the primary document containing necessary information about an AIF for prospective investors. The prescribed framework includes disclosure of management fees, hurdle rate, additional return or carried interest, catch-up and distribution waterfall.
Look specifically for:
- Carry percentage
- Hurdle rate
- Preferred return
- Catch-up
- Waterfall
- Return of capital
- Clawback
- Fee calculation basis
- Gross or net calculation
- Deal-by-deal or aggregate portfolio methodology
- Different terms for different classes of units
What Should Investors Compare Across AIF Fee Structures?
When comparing an AIF, don't stop at "management fee + 20% carry."
Review the complete economics.
Ask:
- Is there a hurdle?
- Is it hard or soft?
- Is there a full or partial catch-up?
- Is carry calculated deal by deal or across the whole fund?
- When does the manager receive carry?
- Is there a clawback?
- Are management fees charged on committed capital or deployed capital?
- What expenses are charged separately?
- Are returns shown gross or net?
- Are there different fee terms for different unit classes?
- What happens if the fund generates gains and then gives them back?
SEBI has emphasised detailed fee and waterfall disclosure in AIF documentation, including illustrative examples for investors.
For an HNI, this level of detail can make the difference between understanding a fund's headline performance and understanding the economics that actually reach the investor.
Final Takeaway
Carried Interest in AIF is not simply a "20% fee". It is a complete economic mechanism involving hurdles, preferred returns, catch-ups, waterfalls, timing and potential clawbacks.
For investors, the smarter approach is to read beyond the headline management fee and carry percentage. Examine the actual distribution waterfall, calculate what happens under different return scenarios and compare the expected investor outcome on a net basis.
ALTPORT can help investors access information and compare available investment opportunities through its investment platform and selection layer. The objective is to make the due-diligence process clearer so investors can examine the structure before making their own investment decision.
Disclaimer
This article is provided for informational and educational purposes only and should not be treated as investment, legal, tax or accounting advice. AIF terms, fees, carry, hurdle rates, distribution waterfalls and tax treatment can vary across funds and investor classes and may change over time. The numerical examples are illustrative and do not represent the terms or expected returns of any specific AIF. Investments in AIFs involve risks, including possible loss of capital, illiquidity and market or investment-specific risks. Investors should review the relevant PPM, contribution agreement and other fund documents and consult qualified professional advisers where required.
ALTPORT is an APMI-registered investment platform/distributor and does not advise, suggest or advertise any investment product. ALTPORT does not guarantee or claim returns and is not a chartered accountant. ALTPORT does not represent a product issuer or authorised channel partner where applicable. Final investment decisions remain solely with the investor.