Building substantial wealth requires more than identifying attractive investments. High-net-worth individuals (HNIs) must decide how to distribute capital across asset classes, manage liquidity, control portfolio risk and align investments with long-term financial objectives. A structured approach to HNI asset allocation India helps investors connect individual investment decisions with an overall wealth-creation strategy.
An effective portfolio should balance growth, income, capital preservation and access to cash. It must also account for existing property holdings, business interests, family obligations, tax considerations and investment time horizons.
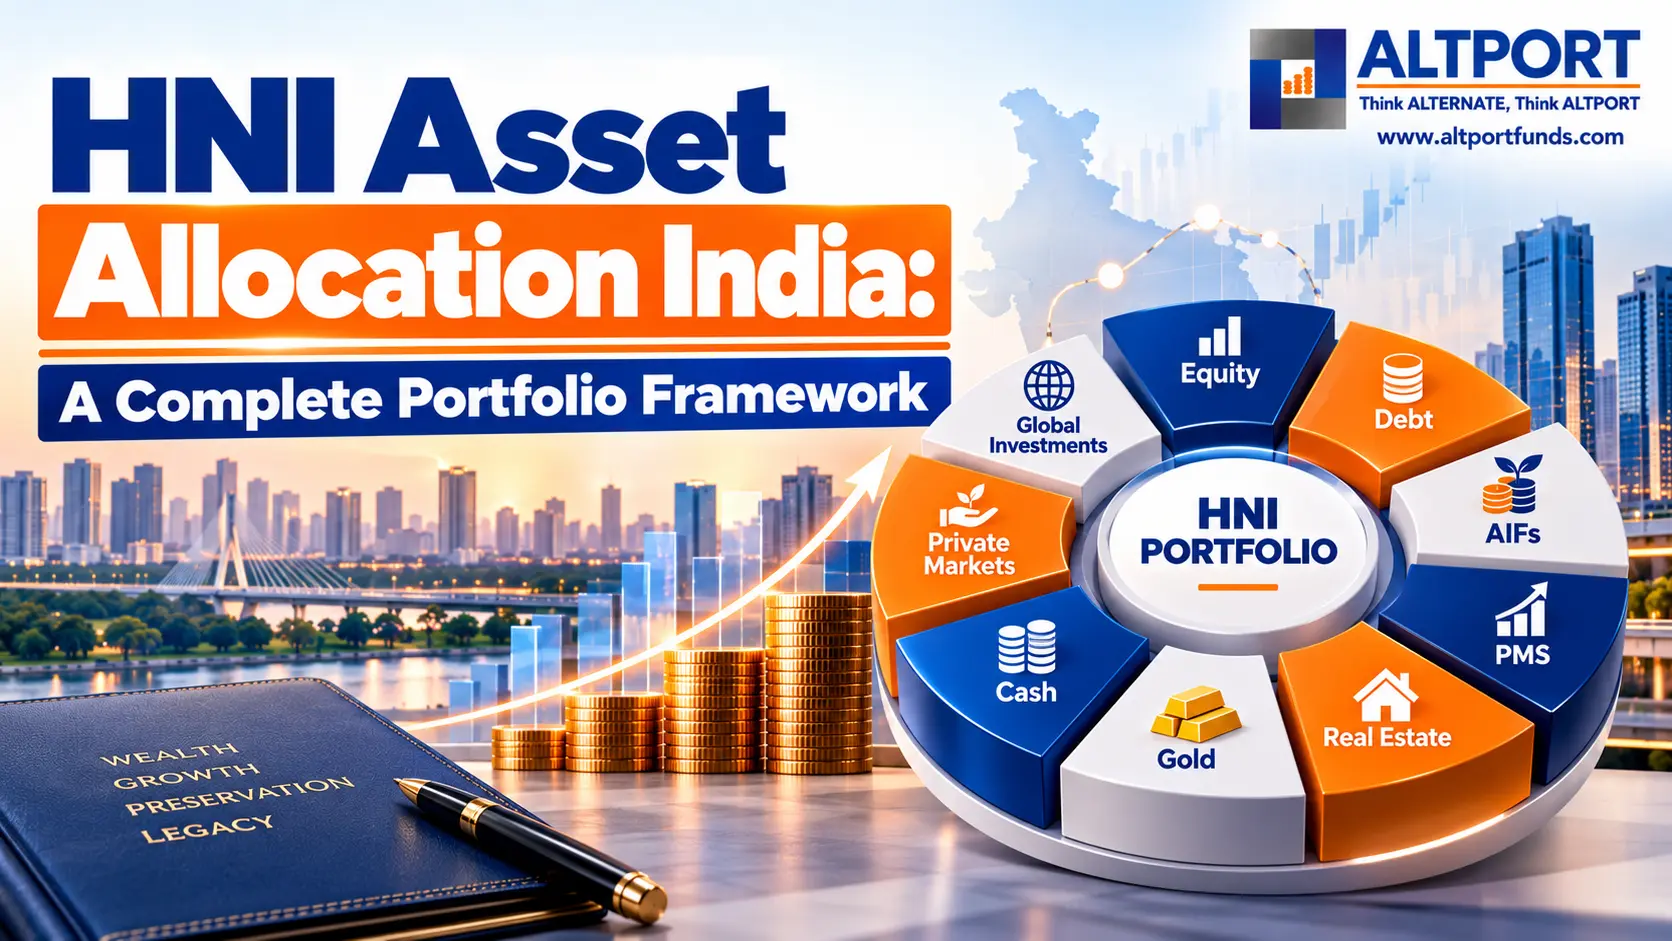
For Indian HNIs and ultra-high-net-worth individuals (UHNIs), the opportunity set extends beyond conventional equity and debt investments. Portfolio management services (PMS), alternative investment funds (AIFs), real estate, gold, private markets and global investments may serve specific portfolio objectives.
Common HNI investment options in India include listed equity, mutual funds, bonds and fixed income, PMS, AIFs, SIFs, real estate, gold, international investments and other suitable alternative investments. Learn more about HNI meaning, wealth thresholds and investment options in India.
However, higher wealth does not automatically justify greater complexity or risk. The right HNI asset allocation India framework begins with the investor's needs and determines which investments deserve a place in the portfolio.
What Is HNI Asset Allocation?
HNI asset allocation is the process of distributing investable wealth across asset classes according to financial objectives, risk tolerance, liquidity requirements and investment horizon.
The purpose of HNI asset allocation India is to create a coordinated portfolio rather than a collection of disconnected investments. Each asset class should perform a defined role.
For example:
- Equity: Long-term capital appreciation.
- Debt: Income generation, portfolio stability and liquidity, depending on the instrument.
- AIFs: Access to selected private-market, credit, venture capital or other alternative strategies.
- PMS: Professionally managed, individually held securities portfolios.
- Real estate: Potential rental income, capital appreciation and tangible-asset exposure.
- Gold: Diversification and a potential hedge against certain market or inflationary pressures.
- Cash and liquid instruments: Emergency requirements, planned expenses and investment opportunities.
The appropriate HNI portfolio allocation depends on the total financial picture, not simply the investor's wealth category.
How HNIs Set Portfolio Objectives and Constraints
A successful HNI investment strategy starts with a written investment policy. Before selecting funds or securities, investors should establish what their capital must achieve.
Important objectives include:
- Growing wealth over a defined period.
- Generating predictable cash flows for lifestyle expenses.
- Preserving capital needed for family commitments.
- Funding business ventures, philanthropy or succession plans.
- Diversifying concentrated business or property exposure.
- Maintaining liquidity for emergencies and planned investments.
The HNI portfolio management process must also identify constraints, including tax liabilities, investment restrictions, debt obligations, family preferences and acceptable drawdowns.
An investor whose wealth is concentrated in a family business may require a different allocation from someone whose assets are already diversified across listed securities and financial instruments.
Similarly, UHNI asset allocation may involve family trusts, succession planning, international exposure and multiple generations of financial objectives. Investors looking at this level of portfolio complexity can also review ALTPORT's guide to Ultra HNI investors in India.
A disciplined HNI asset allocation India plan should document the target allocation, permitted deviations, liquidity requirements, review frequency and conditions that trigger rebalancing.
An Investment Policy Statement (IPS) can formalise these decisions by documenting objectives, risk tolerance, liquidity requirements, strategic asset allocation, concentration limits and rebalancing rules. Learn more about the family office investment committee and IPS framework.
Strategic Asset Allocation Across Equity, Debt and Alternatives
Strategic asset allocation establishes the long-term portfolio structure. It determines how much capital should be assigned to growth assets, income-generating investments, diversifiers and liquidity reserves.
The following framework illustrates the role of different assets. It is a planning illustration, not a prescribed allocation for every HNI.
| Asset class | Primary portfolio role | Key considerations |
|---|---|---|
| Listed equity | Long-term growth | Volatility, valuation and concentration |
| Debt and fixed income | Income and stability | Credit quality, duration and reinvestment risk |
| AIFs and private markets | Strategy diversification and potential growth | Lock-ins, fees and valuation uncertainty |
| PMS | Individualised securities exposure | Manager skill, concentration and costs |
| Real estate | Tangible assets and potential rental income | Transaction costs and illiquidity |
| Gold | Diversification | Price volatility and absence of contractual income |
| Cash and liquid instruments | Immediate liquidity | Inflation and reinvestment risk |
| Global investments | Geographic and currency diversification | Currency, regulatory and market risks |
Official data sources: SEBI – Alternative Investment Funds Regulations; SEBI Investor – Portfolio Management Services.
The framework for HNI asset allocation India should distinguish between an investor's total net worth and investable financial assets. A primary residence, operating business or inherited property may represent substantial wealth but cannot necessarily fund near-term expenses.
HNI asset allocation by corpus size can also differ significantly. A ₹1 crore, ₹5 crore or ₹10 crore portfolio may require different product choices because minimum investment thresholds, liquidity needs and diversification requirements affect the practical allocation.
Risk profile and life stage are equally important. The allocation for a growth-oriented HNI with a long investment horizon may differ from that of an investor approaching retirement, funding major family commitments or prioritising capital preservation.
Role of PMS and AIFs in an HNI Portfolio
PMS and AIFs can expand the range of available investment strategies, but they serve different purposes and carry different risks.
For a detailed comparison of their structure, ownership, liquidity, minimum investment and taxation, see ALTPORT's guide to AIF vs PMS.
Portfolio Management Services (PMS)
PMS provides professional management of an individual client's portfolio. Depending on the mandate, the portfolio may focus on listed equities, other permitted securities or a defined investment strategy.
Before making an HNI PMS allocation, investors should evaluate the investment philosophy, portfolio concentration, benchmark, drawdown history, fee structure, turnover and reporting practices.
PMS costs should also be assessed at the total portfolio level, including management fees, performance-linked fees, brokerage, transaction expenses, custody and applicable taxes. Investors can review ALTPORT's detailed guide to PMS fees and charges in India.
Alternative Investment Funds (AIFs)
AIFs pool capital under a defined investment mandate. Their strategies may include venture capital, private equity, private credit, real estate and market-linked trading strategies, depending on the category and scheme.
An HNI AIF allocation should be evaluated for its underlying strategy, manager experience, portfolio construction, leverage, fees, capital-call obligations, valuation methodology and exit arrangements.
An HNI alternative investment allocation should complement existing holdings rather than simply add more products. For instance, a private-equity fund may increase exposure to businesses already represented in an investor's direct holdings.
Investors must also account for applicable eligibility requirements and minimum investment thresholds. Under the general SEBI AIF framework, the minimum investment is ordinarily ₹1 crore per investor, subject to applicable regulatory exceptions. See the detailed guide to AIF minimum investment in India. SEBI's PMS framework specifies a minimum investment of ₹50 lakh for conventional PMS. Investors can also review PMS minimum investment in India for the applicable rules and exceptions.
For investors comparing AIFs with the newer Specialised Investment Fund structure, the SIF vs PMS vs AIF comparison can help explain the differences in minimum investment, liquidity, ownership and taxation.
The central principle of HNI asset allocation India is to assess the economic exposure beneath each product, not just the product label.
Private Markets, Real Estate, Gold and Cash Allocation
Alternative investments can improve diversification, but they may also introduce illiquidity, complexity and overlapping risks.
Private markets
Private equity, venture capital and private credit may provide access to investments unavailable through conventional listed markets. However, capital may remain committed for extended periods, exits can be uncertain and reported valuations may not reflect immediately realisable prices.
A broader HNI allocation may also consider private equity, private credit, venture capital, REITs, InvITs, pre-IPO or unlisted investments and selected structured products, depending on the investor's objectives, eligibility, liquidity needs and risk tolerance.
Real estate
HNI real estate allocation should consider direct property, rental assets and listed real estate investment trusts (REITs), where suitable. Investors should evaluate location, financing, vacancy, maintenance, transaction costs and concentration.
A property-rich household may already have significant exposure to Indian real estate through its residence and business premises. Additional property investment should be assessed against that existing exposure.
For UHNIs considering a broader mix of real estate, REITs, InvITs, fixed income and alternatives, ALTPORT's Ultra HNI investment profile and allocation guide provides related portfolio context.
Gold
HNI gold allocation can provide diversification, but the investment vehicle matters. Physical gold, exchange-traded products and other permitted routes differ in costs, liquidity, custody and tax treatment.
Cash
HNI cash allocation should reflect upcoming expenses, emergency requirements, tax payments, capital calls and planned purchases. Excessive cash may reduce long-term purchasing power, while insufficient liquidity can force investors to sell assets at unfavourable times.
Tax-aware asset allocation should also consider the difference between pre-tax and post-tax returns. The tax treatment of AIF income can vary by category and income type, making post-tax outcomes relevant when comparing alternative strategies. Investors can review ALTPORT's guide to AIF taxation in India.
A robust HNI asset allocation India approach considers the combined effect of these holdings on the household's liquidity, concentration and downside risk.
Liquidity Buckets for HNI and UHNI Investors
Liquidity planning separates money according to when it may be needed.
| Liquidity bucket | Indicative time horizon | Typical purpose |
|---|---|---|
| Immediate | 0–12 months | Household expenses, emergencies and taxes |
| Intermediate | 1–3 years | Planned purchases and foreseeable commitments |
| Long-term | 3–7 years | Growth-oriented financial goals |
| Extended horizon | 7+ years | Long-term wealth creation and selected illiquid investments |
These horizons are illustrative. Actual requirements depend on the investor's cash flows and liabilities.
A practical approach to HNI asset allocation India is to fund near-term obligations with suitable liquid assets before committing capital to long-duration strategies.
Family office asset allocation may require additional reserves for business contingencies, philanthropy, intergenerational transfers and scheduled capital commitments. Family office portfolio construction in India provides additional context on asset allocation, liquidity and alternatives for HNI and UHNI families.
UHNIs should also distinguish between liquid financial assets and wealth tied up in private businesses or property.
AIF investors should also distinguish between committed, called and invested capital. Future capital calls can create liquidity requirements even when the amount has not yet been deployed. ALTPORT's guide to AIF capital-call liquidity planning covers this issue in greater detail.
Strategic vs Tactical Asset Allocation
Strategic asset allocation establishes the long-term portfolio targets. Tactical asset allocation permits measured deviations when valuations, market conditions or opportunities change.
| Feature | Strategic allocation | Tactical allocation |
|---|---|---|
| Objective | Maintain long-term portfolio alignment | Capture selected opportunities or manage risks |
| Time horizon | Multi-year | Usually shorter-term |
| Decision basis | Goals, risk tolerance and liabilities | Market conditions and defined investment views |
| Main risk | An unsuitable long-term target | Poor timing and excessive trading |
| Governance | Formal investment policy | Defined limits and review requirements |
Tactical decisions should not repeatedly override a sound investment policy. Otherwise, investors risk turning a diversified portfolio into a series of market-timing bets.
For HNI asset allocation India, a useful discipline is to define permissible allocation ranges and require a documented investment rationale for tactical deviations.
Rebalancing, Risk Budgets and Drawdown Limits
Over time, market movements can push a portfolio away from its target allocation. Rebalancing restores the intended risk profile by reducing overweight exposures or adding to underweight assets.
Investors can use calendar-based reviews, allocation bands or event-driven reviews. Tax implications, transaction costs, exit restrictions and liquidity must be considered before executing changes.
Risk budgets define how much exposure the portfolio can tolerate across assets, sectors, managers and strategies. Drawdown limits establish review or escalation thresholds when losses exceed predetermined levels.
Neither a drawdown limit nor diversification guarantees that losses will be avoided. Illiquid assets can also delay the recognition of losses.
A disciplined HNI portfolio management process should monitor the underlying holdings, look-through sector exposure, leverage, currency exposure, manager concentration and total portfolio liquidity.
For a deeper explanation of portfolio drawdowns, recovery periods and liquidity during market corrections, see Managing Portfolio Drawdowns for HNI and UHNI Investors.
Illustrative HNI Portfolio Allocation
The following hypothetical framework demonstrates how an investor might organise a diversified portfolio. It is an educational example, not a model portfolio or investment recommendation.
Illustrative allocations can vary by corpus size, risk profile and life stage. The framework is for educational purposes and is not an investment recommendation.
| Asset class | Illustrative allocation |
|---|---|
| Listed equity | 35% |
| Debt and fixed income | 25% |
| AIFs and private markets | 15% |
| PMS | 10% |
| Real estate and REITs | 5% |
| Gold | 5% |
| Cash and liquid instruments | 5% |
| Total | 100% |
Official data sources: SEBI – AIF Regulations; SEBI Investor – PMS.
The percentages above are illustrative assumptions, not allocations derived from SEBI or another regulator. Actual suitability depends on age, income, liabilities, risk tolerance, existing business and property exposure, and the time available to meet financial goals.
Investors should also examine overlap between PMS, direct equity holdings and AIFs. Adding more products does not necessarily increase diversification. A consolidated review of underlying holdings can help identify duplicated stocks, sectors, themes or risk factors. See ALTPORT's guide to PMS and AIF portfolio overlap for HNIs.
HNI Portfolio Review Checklist
Use this checklist during a periodic portfolio review:
- Are the portfolio's objectives and time horizons still relevant?
- Does the current allocation match the investment policy?
- Is equity exposure diversified across sectors and companies?
- Are debt holdings assessed for credit and interest-rate risk?
- Are AIF and PMS mandates, fees and performance disclosures reviewed?
- Are private-market capital calls and exit restrictions documented?
- Is property concentration consistent with the overall wealth plan?
- Are cash reserves adequate for foreseeable liabilities?
- Have tax, succession and estate-planning requirements changed?
- Are rebalancing rules and drawdown thresholds being followed?
- Is international exposure appropriate for the investor's objectives and currency requirements?
- Has the combined PMS, AIF and direct-equity portfolio been checked for underlying overlap?
For investors considering international diversification, ALTPORT's guide to International equity investment for HNIs covers global equity exposure, currency diversification, LRS and GIFT City structures.
A structured HNI asset allocation India review should focus on changes in financial circumstances, underlying portfolio risks and progress towards objectives—not just recent returns.
Conclusion: Build a More Disciplined Wealth Framework with ALTPORT
Effective wealth management requires a portfolio-wide view of risk, liquidity, opportunity and long-term objectives. A well-designed HNI asset allocation India framework can help investors assess conventional investments alongside PMS, AIFs, real estate, gold and other suitable alternatives.
HNI investment planning should therefore consider not only individual products but also portfolio construction, diversification, liquidity, taxation, concentration and long-term financial objectives.
ALTPORT helps investors explore the alternative investment landscape and evaluate opportunities through a more structured investment lens. Before committing capital, compare the investment mandate, manager experience, fees, liquidity, risk disclosures and suitability for your financial objectives.
Visit us to explore alternative investment opportunities and take a more informed approach to portfolio construction.
Disclaimer
This article is for educational and informational purposes only and does not constitute investment advice, a recommendation to buy or sell any security, or a guarantee of returns. The allocation percentages are hypothetical illustrations and may not be suitable for any particular investor. Investments in securities and alternative investment products involve market, credit, liquidity and other risks, including possible loss of capital. Investors should review applicable offer documents and regulatory disclosures and consult appropriately qualified financial, tax and legal professionals before investing.